
Relatório gerencial em inglês SNCI11 de agosto de 2026
Relatório gerencial em inglês do Suno Recebíveis Imobiliários (SNCI11), fundo imobiliário de papel, referente a agosto de 2026, com entrega no FundosNet (B3) em 28/09/2026. No pregão de 03/11/2026, a cota do SNCI11 fechou a R$ 78,77, com P/VP de 0,82 (valor patrimonial de R$ 96,06 por cota no informe mensal de setembro de 2026). O último rendimento foi de R$ 1,00 por cota, com pagamento em out/2026, e o dividend yield dos últimos 12 meses é de 13,96% sobre a cotação de 03/11/2026. O patrimônio líquido era de R$ 403,5 milhões no informe mensal de setembro de 2026. Os indicadores são os mais recentes da base do Kartac, não os do período do documento.
Informações
- CNPJ
- 41.076.710/0001-82
- Tipo
- Outras Informações
- Assunto
- Relatório gerencial em inglês
- Data de referência
- 31/08/2026
- Data de entrega
- 28/09/2026 18:33
- Versão
- 1
- Situação
- (Ativo)
Conteúdo
ASNCH
M A N A G E M E N T R E P O R T
AUGUST 2026
14.73%
based on market price
CO NTE NTS
- Executive Summary 03
- Manager's Letter 04
- Macro & Real Estate Backdrop 08
- Portfolio Summary 09
- Asset Portfolio 11
- Accounting Information 13
- Trading, Liquidity & Yields 14
- Asset Monitoring 15
- Asset Detail 17
- AGTs 18
- Learn More / FAQ 19
- Glossary 21
SNCI11 Management Report — August 2026
EXECUTIVE SU M MARY SUNO(ASSET)
Manager Suno Gestora de Recursos LTDA Administrator BTG Pactual Serviços Financeiros S.A. Fund Inception October 2021
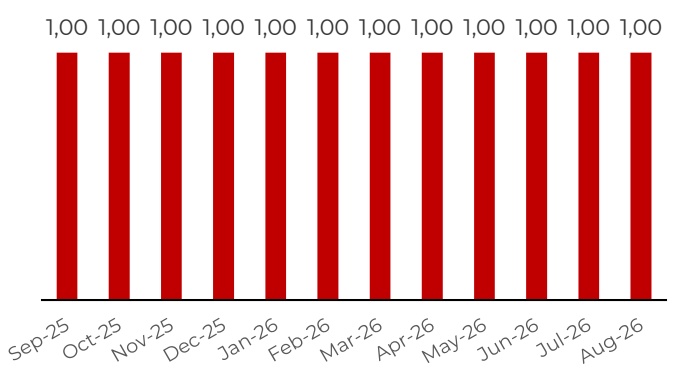
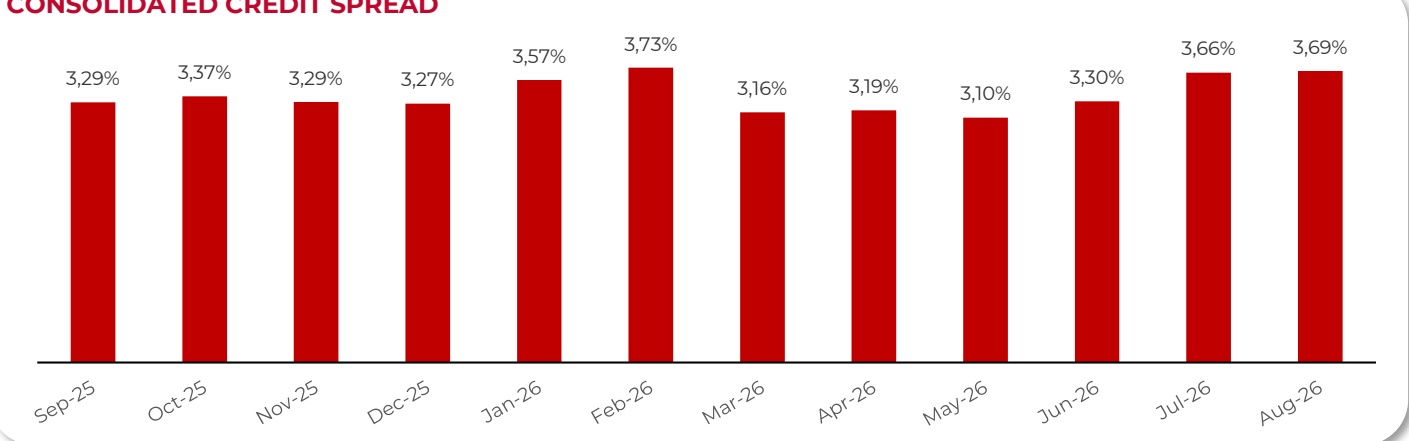
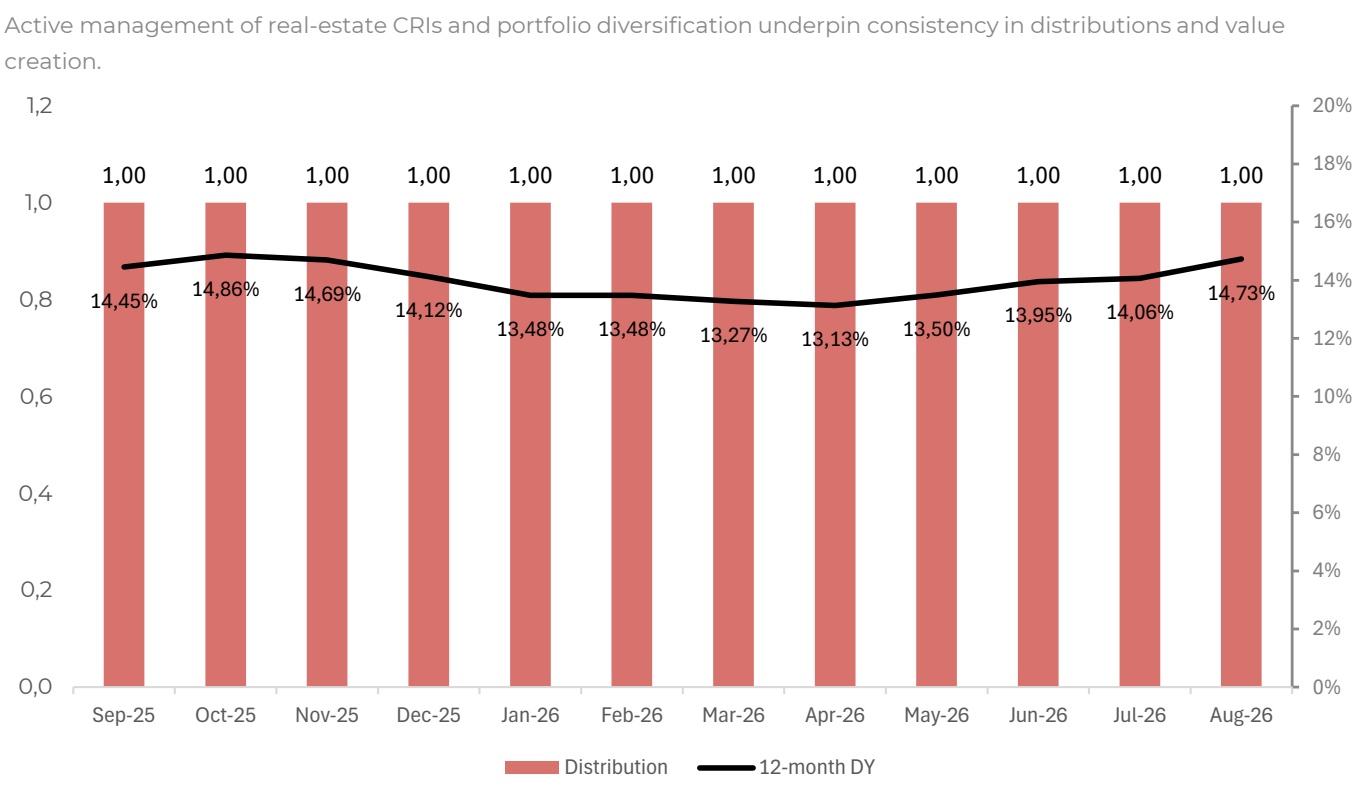
In August, the Fund distributed R$ 1.00 per unit, in line with the guidance of R$ 1.00 to R$ 1.10 for 3Q26. The annualized DY (dividend yield) closed at 14.73% on the market price, with the unit trading at R$ 81.48 (0.85x P/VP, price-to-NAV). The consolidated credit spread was 3.69%, slightly above the previous month and reflecting the easing after the 5.4% peak in 2H25, still at a healthy level. Net leverage ended the month negative at -2.90% of NAV (PL), with the Fund as a net creditor in repos (R$ -11.60 MM). Management was active in the CRI holders’ meetings, notably on resolutions for the LocPay, Gafisa Sorocaba, Supreme Garden, Bit and AIZ CRIs. The Fund ended the month with four assets under special treatment: CRI AIZ, CRI Vanguarda, CRI RDR and CRI Solar Junior.
Distribution History (R$)
Number of Unitholders
Dividend Yield (annualized) 14.73%
Distribution per Unit
Net Assets
R$ 400.59 MM
R$ 1.00
Assets in Portfolio 50
P/VP 0.85
Market Price / NAV per Unit R$ 81.48 / R$ 95.38
Weighted Average LTV 61.41%
Market Value
Closing Cash
R$ 342.22 MM
Average Portfolio Yield 17.03%
R$ 22.67 MM
Accumulated Profit
Units outstanding: 4,200,000
R$ 0.46
Number of Unitholders
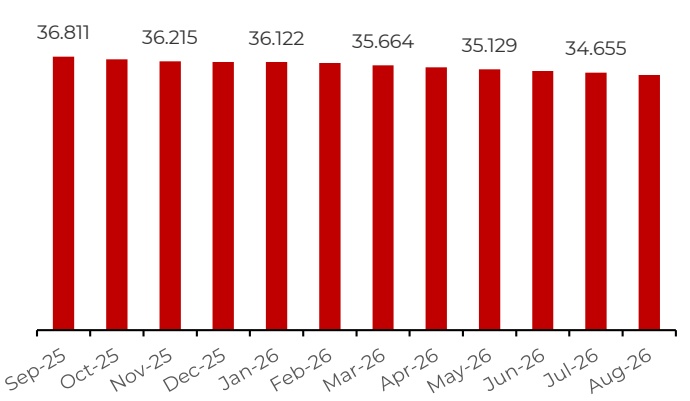
34,345
Manager's Letter — August 2026
SNCI11 – Suno Recebíveis Imobiliários FII | Information through mid-September 2026
Highlights of the month
Result of R$ 1.37/unit, above the distribution of R$ 1.00/unit; the accumulated reserve rises to R$ 0.46/unit. 3Q26 guidance maintained between R$ 1.00 and R$ 1.10/unit.
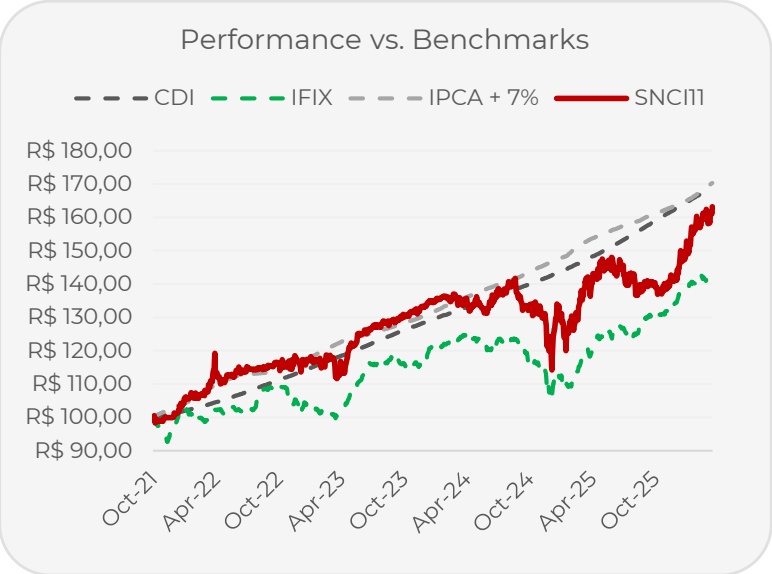
Market price: −3.36%, versus −1.46% for the IFIX; P/VP of 0.85 and NAV per unit of R$ 95.38.
Supreme Garden, BIT Barueri and Gafisa Sorocaba (22.2% of NAV) obtained waivers and maturity extensions at AGTs (CRI holders’ general meetings); at BIT, the Fund’s series become subordinated to a new R$ 15 million senior series, also allocated proportionally by the Fund.
Recovery at RDR: 9th round of R$ 23.5 thousand on August 25, one debt acknowledgment already being paid and 10th round of R$ 700 thousand set for September 25.
R$ 34.5 million in net purchases and R$ 16.8 million in sales.
• Cash of R$ 22.7 million (5.7% of NAV), with the Fund a net creditor: net leverage of −2.90% of NAV.
Performance
| Adjusted return | August 2026 | 12 months |
|---|---|---|
| SNCI11 — market price | -3.36% | 11.55% |
| SNCI11 — NAV per unit | 0.72% | 5.68% |
| IFIX | -1.46% | 8.24% |
The market price fell more than the IFIX, and the P/VP moved from 0.91 to 0.85, a decline observed in the repricing of paper FIIs (CRI-focused real-estate funds) as the yield curve shifted upward in August, in addition to the impacts of the conservative marking of the RDR CRI credit novations. In the NAV per unit, R$ 0.37 of the R$ 1.11/unit increase comes from retained earnings and the remainder from portfolio marking, including the unwinding of the GFSA3 transaction, with no gain or loss to the Fund, with an impact on the partial amortization of the CRI in the month.
Result and distribution
| Result for the month | Aug/26 distribution | Reserve after distribution | Sep/26 distribution | 3Q26 guidance |
|---|---|---|---|---|
| R$ 1.37/unit | R$ 1.00/unit | R$ 0.46/unit | R$ 1.00/unit | R$ 1.00 to R$ 1.10/unit |
The result of R$ 5.75 million comprised R$ 2.82 million of trading gains, R$ 2.11 million of CRI interest, R$ 0.33 million of inflation adjustment and R$ 0.37 million from FIIs. Expenses fell to R$ 0.20 million with the R$ 150 thousand management fee waiver (see Additional considerations). For September, we announced a distribution of R$ 1.00/unit and reaffirmed the published guidance.
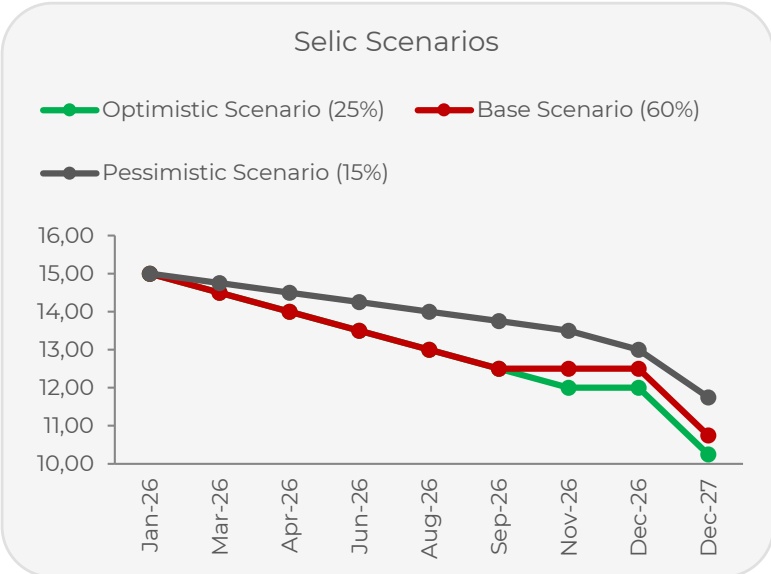
Interest rates: on September 16, Copom cut the Selic to 13.75% p.a. With 21.4% of NAV in CDI-linked CRIs and 5.7% in cash, each 0.25 p.p. of Selic moves revenue by under R$ 0.01/unit/month.
Portfolio movements
| Transaction | Type | R$ mm | Rate / price | Comment |
|---|---|---|---|---|
| CRI GS Souto | Net purchase | 16.54 | IPCA + 11.13% | Position rises to 6.22% of NAV |
| CRI Oliveira | Purchase | 8.12 | IPCA + 12.68% | New tranche, from the previous pipeline |
| CRI LocPay II (senior) | Purchase | 2.18 | CDI + 5.50% | New series, from the previous pipeline |
| CRI-focused Flls (basket of four funds – see Allocation) | Purchase | 7.69 | P/VP from 0.57 to 0.78 | Paper Flls trading at a discount |
| CRIs MZM II and MZM V | Sale | 16.78 | IPCA + 12.00% | Sale of series V to adjust the position |
Liquidity: cash of R$ 22.67 million (5.66% of NAV) and R$ 11.06 million in repo borrowings, with SNCI11 a net creditor of R$ 11.60 million (net leverage of −2.90% of NAV). There were no payoffs in the month.
Pipeline
| Transaction | Amount | Expected rate | Stage | Expected timing |
|---|---|---|---|---|
| Construction-completion CRI, developer in Vila Velha/ES | up to R$ 10 mm | CDI + 6.00% | Being structured | September 2026 |
| 5th senior series of CRI BIT Barueri (R$ 15 mm approved at AGT) | up to R$ 4 mm | CDI + 5.50% | Approved at AGT | September 2026 |
| Senior CRI – assignment of a performing portfolio | up to R$ 32 mm | IPCA + 10.85% | Under approval | September 2026 |
| Corporate real-estate development CRI | up to R$ 3 mm | CDI + 4.90% | Under negotiation | October 2026 |
| Contributions to complete construction at MZM | up to R$ 5 mm | IPCA + 12.95% | Contingent | October 2026 |
In August, the Fund executed the previous pipeline in Oliveira (R$ 8.1 million), LocPay (R$ 2.2 million) and CRI-focused FIIs. Vila Velha and Bit come in above the portfolio’s CDI average (CDI + 6.00%, versus CDI + 5.49%). The transactions may not materialize for various reasons.
Additional considerations
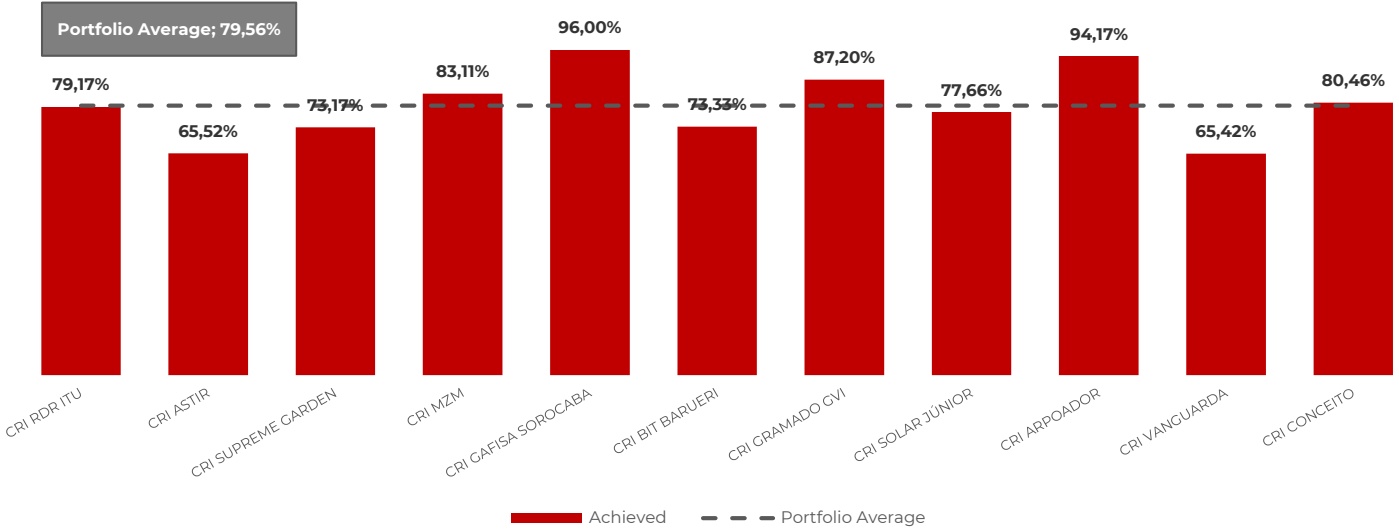
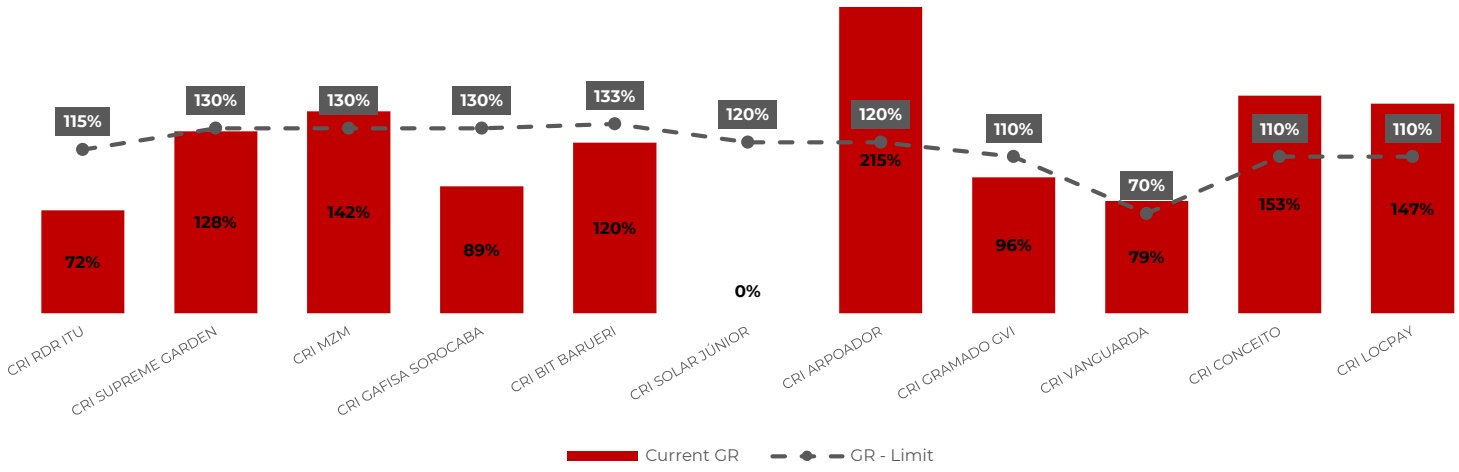
Construction in the final stretch. Supreme Garden, BIT Barueri and Gafisa Sorocaba together account for 22.2% of NAV, obtained waivers and maturity extensions in August and have guarantee ratios below the contractual limit. Nevertheless, the occupancy permit (“Habite-se”) is expected for Supreme Garden and Bit still in 2026, with the start of the onlending of buyers’ financing (repasses) and the reduction of the outstanding balance. Although out of compliance, the Guarantee Ratios of both transactions continue to provide a safety margin relative to the outstanding balance of the CRIs. Additional collateral is being considered for the Gafisa Sorocaba transaction, whose occupancy permit is expected for October 2026. The transaction is backed by a guarantee (aval) from Gafisa S.A.
| Transaction | % of NAV | Construction | Sales | Current GR / limit |
|---|---|---|---|---|
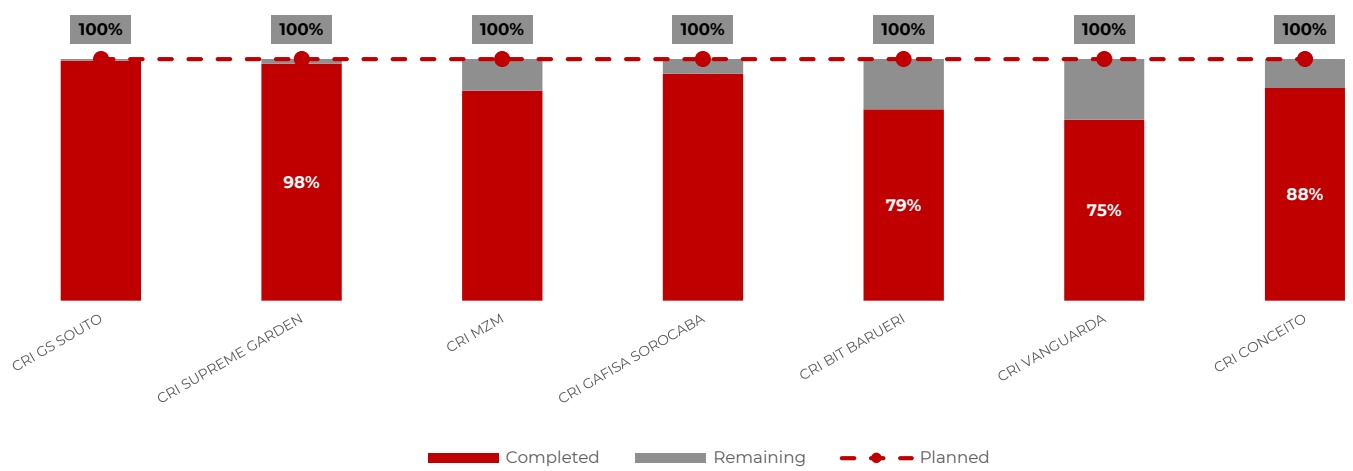
| CRI Supreme Garden | 8.47% | 98.2% | 73.2% | 127.8%/130% |
| CRI BIT Barueri | 7.94% | 79.2% | 73.3% | 119.8%/133% |
| CRI Gafisa Sorocaba | 5.84% | 94.0% | 96.0% | 89.1%/130% |
MANAGER'S LETTER
Management fee waiver. In August, the Manager waived R$ 150 thousand of the Fund’s management fee, the first of two installments returning to unitholders the revenue earned by Suno S.A. from structuring the CRI Mahalo, settled in May. Thus, part of Suno S.A.’s structuring revenue from this security will be passed on to SNCI11 in proportion to its investment in the CRI.
Resolutions at AGTs
Full agenda in the AGTs of the Month section.
| Asset | Date | Resolution | Vote | Effect on SNCI11 |
|---|---|---|---|---|
| CRI LocPay | August 4 and 17, 2026 | 3rd and 4th series move from 23.87% fixed-rate to CDI + 5.50% p.a. (re-ratified on August 17) | In favor | Correction of an issuance error |
| CRI Gafisa Sorocaba | August 12, 2026 | Maturities extended from January 2027 to July 2027, with a restructuring fee charged | In favor | Extends the transaction given the construction delays |
| CRI Supreme Garden | August 19, 2026 | Suspension of the acceleration, 90 days to replenish the transaction's reserve funds and restore GR compliance until the occupancy permit (November 30, 2026) | In favor | Preserves more value than mandatory redemption |
| CRI BIT Barueri | August 26, 2026 | 5th senior series of R$ 15 mm (CDI + 5.50%) to complete construction; 1st to 4th series subordinated, maturities from April 2027 to July 2027 and waiver fee of R$ 1 mm | In favor | Only source of funds to complete construction |
| CRI AIZ | August 27, 2026 | Warehouse sale deadline extended to October 30, 2026, legal advisor for the sale and voluntary contribution by holders | In favor | See Watchlist |
Watchlist
Assets with acceleration, default or restructuring with a haircut, ordered by market exposure. They total 2.96% of NAV at market.
| CRI AIZ (Pesa) — long and short series | Restructured · Warehouse sale extended to October 30, 2026 | ||
| EXPOSURE 1.44% of NAV· short series under correction by the Administrator | MARKING Series 301 – 80% of the estimated recovery value Series 302 – marked at R$ 0 | EXPECTED RECOVERY NEXT MILESTONE Warehouse sale · by High, after haircuts of ~20% October 30, 2026 and ~48% on the two series | |
| What changed | The AGT of August 27 extended the deadline for the sale of the Warehouse (Galpão) to October 30, 2026, engaged Cescon Barrieu as legal advisor for the sale and maintained the payment terms of the AGT of December 24, 2025, conditional on the sale within that period. Holders approved a voluntary contribution, proportional to their position, for the expenses of the next six months. No contribution has been made yet. In the August marking, the Administrator wrote the short series down to zero without considering the deadline extension approved on December 24, 2025; the correction is underway. | ||
| Status | Final restructuring approved at the AGT of December 24, 2025, with the sale of the main collateral property below the appraisal's forced-sale value. The series with a fiduciary lien will be fully settled with the sale, already with a haircut of ~20%. The series without real collateral was extended for 10 years at CDI + 3.50% p.a., with monthly interest from January 2027 and reinforcement of the remaining collateral (~R$ 10 million at market). Delays in the sale led to three deadline extensions in 2026. | ||
| Effect on SNCI11 | -R$ 0.22/unit on cash result and +R$ 0.26/unit on NAV (estimated); residual expense contribution. | ||
| Next steps | By October 30, 2026: Warehouse sale. Within 60 days after: AGT on the new CCB and CRI schedules. | ||
MANAGER'S LETTER
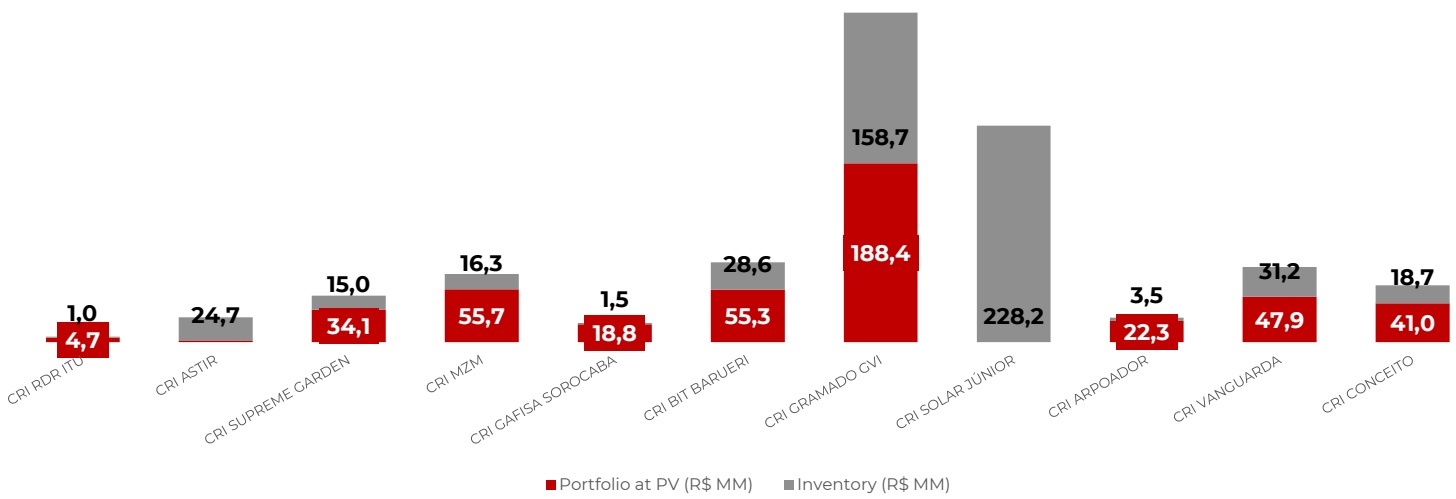
| CRI RDR Itu E0 t mhX.7Pme7O C%S wURRi oItEfh · N c tohAseVt n o aoftv ~ ma | Matured on August 20, 2025 · under recovery, partially novated EXPECTED RECOVERY Portfolio at PV of R$ 4.7 mm Rta$irok 1n6es.t8 in AM reAtcR coKovINseGtr,i ceosn osbidtaeirninedg the + a 1 a3dc i.nk5dvni mteoionmwntloae inrldy c dgo oemlfbla Rettn$etr 1a.0l + m Rm$ + N1 S t0hEetXophTut Mes reamILcnEboSdTev)OerNr 2Ey5 r (oRu$n 7d0 ·0 agreements |
|---|---|
| The 9th recovery round, on August 25, totaled R$ 23.5 thousand across the three series. Installments | |
| What changed | under one of the novation's debt acknowledgment agreements are already being paid. The remaining portfolio has just over R$ 4.7 mm receivable. |
| Status | Construction completed; we chose not to extend the maturity. The March AGT approved the dation in payment (in-kind settlement) of part of the units and the restructuring of part of the CRI into separate debts for each partner and for the company, with R$ 13.5 million novated into three debt acknowledgment agreements. After the outstanding issues are resolved and the final portfolio audit is completed, we will grant a haircut on the updated outstanding balance, with no further NAV or cash effect, because the asset is already marked at cost. |
| Effect on SNCI11 | None on the distribution: the transaction already accrued interest and generated no monthly income in the result. |
| Next steps | September 25: 10th round (R$ 700 thousand). Coming months: debt acknowledgment installments, portfolio collections and sale of additional collateral. After the audit: formal haircut. |
| CRI Vanguarda E0 oXf.6P tO6hS%eUR i osEfs NuaAnVc ·e les | - Jonathan Nunes and Dom Severino Accelerated on August 18, 2025 · under recovery NEXT MILESTONE s than 4% AMAtR cKoINsGt EBXePtEwCTeEeDn R 6EC0O~V7E0R%Y of cost H c poeirmrimnpgilte o (tfHio aanb c aiotnned-tsr oaecc)tcourp faonrcy |
|---|---|
| No AGT in the month. August monitoring shows receivables of R$ 47.9 million and inventory of R$ 31.2 | |
| What changed | million, totaling R$ 79.1 million. Net of the projects' construction-completion costs, recovery is estimated at between 60% and 70% of cost. This marking will be reflected in the portfolio as soon as we have visibility on the resumption of construction of the projects. |
| Status | Acceleration following the diversion of sales by the contractor. All units, except swaps (permutas) and fully paid units, are registered in the name of the securitization company. Jonathan Nunes: construction completed, occupancy permit blocked by documentation issues at Vanguarda Engenharia, with legal action in progress and possible replacement of the technical manager. Dom Severino: 75% executed, site halted until the construction is transferred. |
| Effect on SNCI11 | Contributions proportional to the position, residual and with no effect on the distribution. NAV remarking will be negligible given the low exposure. |
| Next steps | Hiring of a contractor for completion and occupancy permit; contributions per schedule; measures against Vanguarda Engenharia based on the audit. |
| CRI Solar Junior | Matured and in default since November 21, 2025 | ||
| EXPOSURE 0.09% of NAV | MARKING 70% of cost | EXPECTED RECOVERY Not yet estimable | NEXT MILESTONE Receive the legal enforcement plan from the |
| securitization company | |||
| What changed | No new event in the month. The securitization company is conducting the operational and legal recovery measures. We continue to | ||
| Status Effect on SNCI11 | gather information from the securitization company, the fiduciary agent and the majority investors. Extremely residual, given the very low exposure. | ||
Management Team, SUNO ASSET
MACRO & REAL ESTATE BACKDROP
| Selic | 13.75% |
|---|---|
| IPCA (2026e) | 4.22% |
| FX (R$/USD) | R$ 5.18 |
| Brazil GDP (2026e) | 1.9% |
| Unemployment (2026e) | 5.3% |
| Gross Debt (% of GDP) | 82.5% |
PORTFOLIO SU M MARY
Number of Assets in Portfolio 50
Average Leverage Cost CDI + 0.97%
P/VP 0.85
Weighted Portfolio Duration 1.64
Average FII Yield 14.66%
Average CRI Yield (All-In) 17.95%
Net Leverage -2.90% of NAV
Repo Volume R$ -11.60 MM
Avg. Rate IPCA+ CRIs IPCA + 10.72%
Avg. Rate IGPM+ CRIs IGPM + 8.29%
Avg. Rate INCC+ CRIs INCC + 0.00%
Avg. Rate CDI+ CRIs CDI + 5.49%
MAIN PORTFOLIO SECTORS
| Sector | % of NAV |
|---|---|
| Development | 44.9% |
| Energy | 10.7% |
| FIIs | 9.7% |
| Repos | 9.3% |
| Industrial | 6.2% |
| Healthcare | 4.4% |
| Cash | 8.9% |
| Land Subdivision | 2.5% |
| Aviation | 2.1% |
| Other | 1.4% |
EXPOSURE BY INDEX (% NAV)
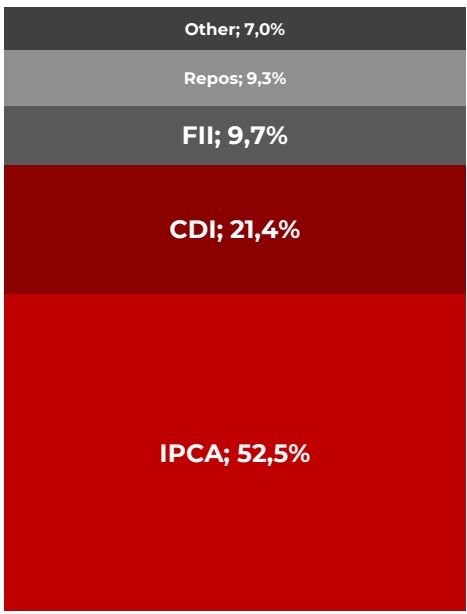
CDI; 21,4%
IPCA; 52,5%
CONSOLIDATED CREDIT SPREAD
PORTFOLIO SU M MARY
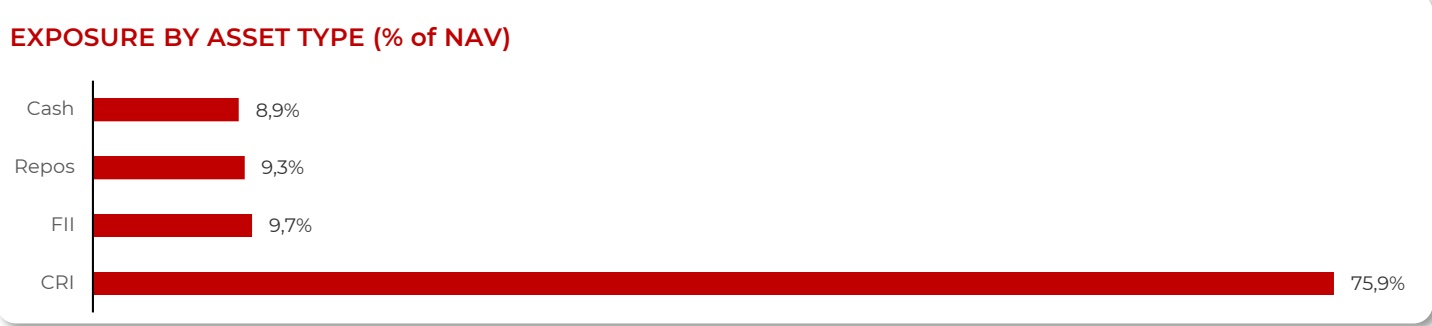
EXPOSURE BY RISK PROFILE (% of NAV)
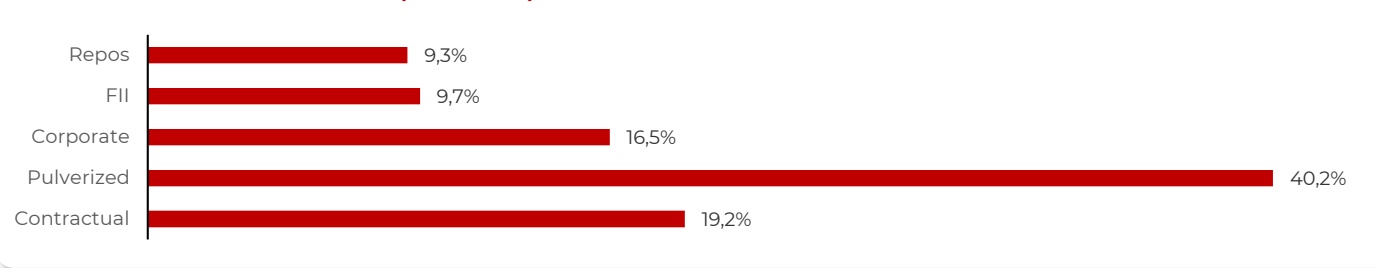
EXPOSURE BY RATING (% of NAV)
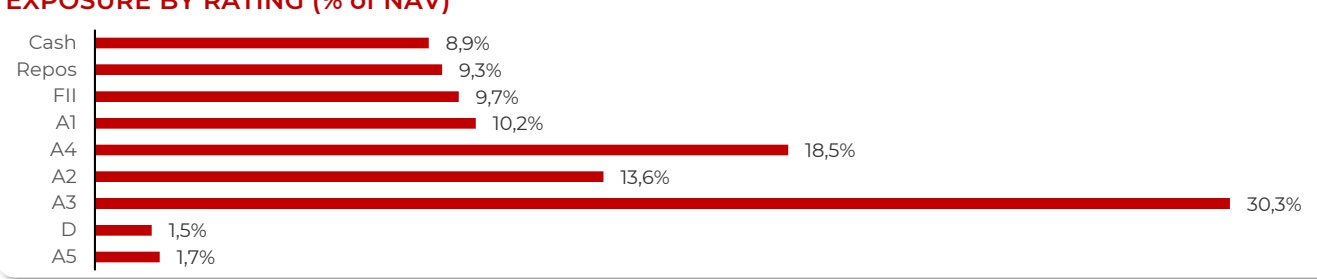
EXPOSURE BY DURATION (% of NAV)
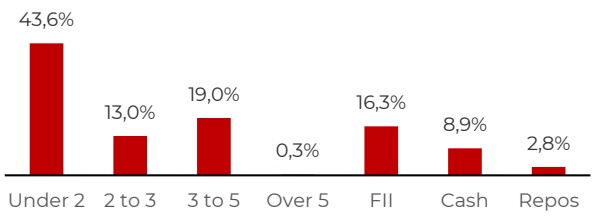
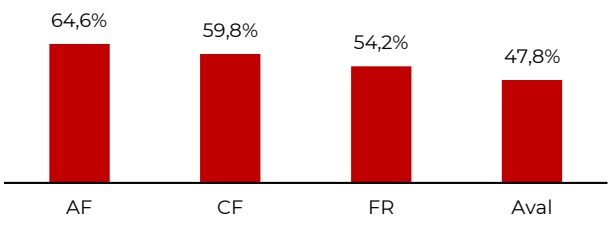
CRI EXPOSURE BY COLLATERAL (% of CRIs)
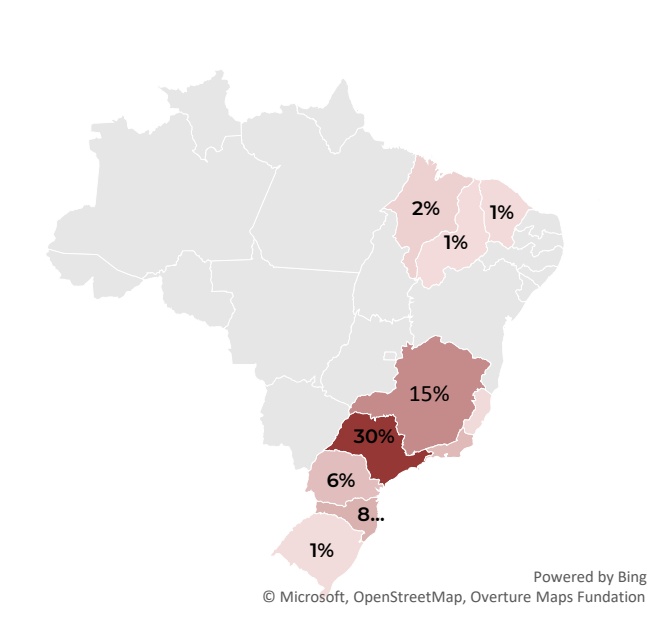
EXPOSURE BY LOCATION
CRI and Asset Portfolio — August 2026
| Asset | Profile | CETIP Code | Sector | Rtg | Idx | Yield MTM | Yield HTM | Dur. | N%AV | LTV |
|---|---|---|---|---|---|---|---|---|---|---|
| CRI SUPREME GARDEN | Pulv. | 22B0338247 | Dev. | A4 | IPCA | 14.88% | 10.50% | 0.21 | 7.65% | 65% |
| CRI GS SOUTO | Contr. | 21K0732283 | Energy | A3 | IPCA | 0.00% | 11.13% | 3.22 | 6.22% | 62% |
| CRI GAFISA SOROCABA (new) | Pulv. | 25L3104624 | Dev. | A3 | CDI | 6.00% | 6.00% | 0.27 | 5.84% | 90% |
| CRI MRV | Corp. | 21D0001232 | Dev. | A3 | IPCA | 12.27% | 5.43% | 3.28 | 5.59% | - |
| CRI CERATTI MAGNA | Contr. | 22E0120555 | Industrial | A1 | IPCA | 9.56% | 9.40% | 0.75 | 4.78% | 60% |
| CRI ITABIRA | Contr. | 23L2160618 | Energy | A2 | IPCA | 11.49% | 11.00% | 4.15 | 4.44% | 95% |
| CRI OPY HEALTH | Corp. | 21H0888186 | Healthcare | A1 | IPCA | 10.03% | 7.36% | 2.10 | 4.38% | 45% |
| CRI OLIVEIRA | Pulv. | 26E4609469 | Dev. | A4 | IPCA | 12.21% | 12.68% | 2.39 | 4.13% | - |
| CRI BIT Series 4 | Pulv. | 22J2609555 | Dev. | A3 | CDI | 5.50% | 5.50% | 0.22 | 3.27% | 60% |
| CRI MRV II | Corp. | 22B0006022 | Dev. | A3 | IPCA | 11.67% | 6.50% | 1.86 | 2.70% | - |
| CRI MZM III | Pulv. | 22I1466156 | Dev. | A4 | IPCA | 12.95% | 12.95% | 0.63 | 2.23% | 70% |
| CRI COMPORTE | Corp. | 23I1270600 | Transport | A2 | CDI | 3.54% | 3.80% | 1.82 | 2.07% | 60% |
| CRI BIT Series 3 | Pulv. | 22J2609554 | Dev. | A3 | CDI | 6.03% | 5.50% | 0.22 | 2.06% | 60% |
| CRI LATAM | Contr. | 21C0818332 | Aviation | A2 | IPCA | 8.75% | 4.50% | 2.63 | 2.05% | 45% |
| CRI MZM | Pulv. | 22I1465810 | Dev. | A4 | IPCA | 13.27% | 12.95% | 0.63 | 1.74% | 70% |
| CRI BIT | Pulv. | 22J1411295 | Dev. | A3 | CDI | 5.50% | 5.50% | 0.22 | 1.67% | 60% |
| CRI MZM II | Pulv. | 22I1466133 | Dev. | A4 | IPCA | 12.18% | 12.95% | 0.63 | 1.54% | 70% |
| CRI PESA / AIZ (Long) | Contr. | 21F0568504 | Industrial | A5 | IPCA | 0.00% | 7.00% | 0.32 | 1.44% | - |
| CRI GF6 | Pulv. | 25G5823976 | Land Sub. | A2 | IPCA | 14.97% | 15.00% | 3.04 | 1.25% | 50% |
| CRI MAHALO | Pulv. | 26D0059264 | Dev. | A2 | CDI | 6.00% | 6.00% | 2.72 | 1.23% | 75% |
| CRI CONCEITO | Pulv. | 25J2612796 | Land Sub. | A2 | CDI | 6.50% | 6.50% | 2.41 | 1.23% | 46% |
| CRI LOCPAY II (SENIOR) | Pulv. | 26F4020125 | Receiv. | A3 | CDI | 5.50% | 5.50% | 3.10 | 1.05% | - |
| CRI LOCPAY (SENIOR) | Pulv. | 25H2417003 | Receiv. | A3 | Fidxe | 23.63% | 23.87% | 1.64 | 1.02% | - |
| CRI MITRE 2025 | Corp. | 25A1810636 | Dev. | A2 | CDI | 1.99% | 3.50% | 1.99 | 1.01% | - |
| CRI BIT Series 2 | Pulv. | 22J1411297 | Dev. | A3 | CDI | 5.50% | 5.50% | 0.22 | 0.94% | 60% |
| CRI SUPREME GARDEN 509 | Pulv. | 25F2808184 | Dev. | A4 | IPCA | 10.58% | 10.50% | 0.21 | 0.82% | 65% |
S N C I 1 1 - S U N O A S S E T
ASSET PORTFOLIO
CRI and Asset Portfolio — August 2026
| Asset | Profile | CETIP Code | Sector | Rtg | Idx | Yield MTM | Yield HTM | Dur. | N%AV | LTV |
|---|---|---|---|---|---|---|---|---|---|---|
| CRI VANGUARDA | Pulv. | 22G1233041 | Dev. | D | INCC | 0.00% | 11.00% | 0.00 | 0.66% | 52% |
| CRI RDR ITU | Pulv. | 21K0660418 | Dev. | D | IPCA | 23.10% | 12.00% | 0.00 | 0.64% | 80% |
| CRI ARPOADOR (SUBORDINATED) | Pulv. | 23J2809383 | Dev. | A1 | CDI | 12.00% | 12.00% | 1.24 | 0.41% | 43% |
| CRI ARPOADOR (SENIOR) | Pulv. | 23J2266231 | Dev. | A1 | CDI | 4.50% | 4.50% | 1.30 | 0.33% | 43% |
| CRI ESTOQUE HELBOR | Corp. | 22H1104501 | Dev. | A2 | CDI | 2.71% | 2.30% | 0.53 | 0.33% | 80% |
| CRI GRAMADO GVI | Pulv. | 21F0950048 | Timeshare | A5 | IPCA | 58.29% | 9.50% | 1.13 | 0.30% | 26% |
| CRI ESATAS | Contr. | 21C0572241 | Infra. | A1 | IGP | 8.29% | 7.56% | 6.79 | 0.28% | 80% |
| REDE DUQUE (Series 443) | Corp. | 21I0855537 | Oil & Gas | A4 | IPCA | 12.85% | 7.25% | 3.06 | 0.22% | 67% |
| REDE DUQUE (Series 444) | Corp. | 21I0855623 | Oil & Gas | A4 | IPCA | 12.90% | 7.25% | 3.06 | 0.22% | 67% |
| CRI SOLAR JUNIOR | Pulv. | 19K1139245 | Timeshare | D | IPCA | 17.42% | 16.64% | 0.00 | 0.09% | 68% |
| C 3RI RDR ITU SERIES | Pulv. | 21K0661041 | Dev. | D | IPCA | 16.69% | 12.00% | 0.00 | 0.07% | 80% |
| C 2RI RDR ITU SERIES | Pulv. | 21K0660445 | Dev. | D | IPCA | 26.71% | 12.00% | 0.00 | 0.05% | 80% |
| CRI Pesa / AIZ (Short) | Contr. | 21F0569265 | Industrial | A5 | IPCA | 0.00% | 5.50% | 0.05 | 0.00% | - |
| FIIs | Sector | Qty. | Price | Yield | Yield on Cost | P/VP | N%AV | Ca%sh | Avg. Cost |
|---|---|---|---|---|---|---|---|---|---|
| SNME11 | Hybrid | 3,731,239 | R$ 9.50 | 13.27% | 12.93% | 0.97 | 4.2% | 26.4% | R$ 9.75 |
| INOI | Logistics | 35,000 | R$ 103.79 | 9.15% | 9.50% | 1.00 | 0.9% | - | R$ 100.00 |
| TGAR11 | Hybrid | 164,474 | R$ 88.29 | 16.85% | 12.24% | 0.43 | 1.3% | 0.1% | R$ 121.60 |
| RECD11 | Paper | 400,000 | R$ 10.00 | 15.01% | 15.01% | 0.86 | 0.5% | 5.7% | R$ 10.00 |
| ZAVC11 | Paper | 57,972 | R$ 9.14 | 18.47% | 16.31% | 0.91 | 0.1% | 13.2% | R$ 10.35 |
| ARRI11 | Paper | 341,561 | R$ 4.81 | 13.21% | 13.66% | 0.57 | 0.4% | 2.1% | R$ 4.65 |
| VCRI11 | Paper | 515,662 | R$ 7.33 | 16.71% | 16.82% | 0.78 | 0.9% | 1.6% | R$ 7.28 |
| VRTM11 | Hybrid | 304,693 | R$ 6.85 | 15.69% | 11.07% | 0.70 | 0.6% | 7.6% | R$ 9.71 |
| GCRI11 | Paper | 30,936 | R$ 66.25 | 16.53% | 16.75% | 0.72 | 0.5% | 1.0% | R$ 65.40 |
| VCJR11 | Paper | 5,792 | R$ 69.09 | 20.87% | 20.96% | 0.75 | 0.1% | 9.0% | R$ 68.79 |
| Repos | - | - | - | - | - | - | 9.3% | - | - |
| REPOS | Profile | CETIP Code | Sector | Idx | Yield HTM | Repo Rate | Vol. (MM) |
|---|---|---|---|---|---|---|---|
| CRI Esatas Viracopos | Contr. | 21C0572241 | Infrastructure | IGP | 8.00% | 8.00% | R$ 8.00 |
| Rede Duque (Series443) | Corp. | 21I0855537 | Oil & Gas | IPCA | 7.25% | 7.25% | R$ 5.00 |
| R 44ed4e) Duque (Series | Corp. | 21I0855623 | Oil & Gas | IPCA | 7.25% | 7.25% | R$ 5.00 |
ACCOU NTI NG I N FORMATION
R$ 5.95 M
Distributable Revenue generated in the month
R$ 1.37
Result/Unit net result for the month
R$ -0.20 M
Expenses fees + operating costs
R$ 1.00 M
Distribution R$ 4.20 MM total distributed
R$ 5.75 M
Final Result R$ 1.37/unit
R$ 1.95 M
Reserve Movement reserve: R$ 0.46/unit
INCOME STATEMENT — AUGUST 2026
| JUN/26 | JUL/26 | AUG/26 | R$/Unit (M0) | LTM | |
|---|---|---|---|---|---|
| DISTRIBUTABLE REVENUE | R$ 5,291,296 | R$ 3,504,273 | R$ 5,946,118 | R$ 1.416 | R$ 59,042,604 |
| Cash Yield | R$ 217,369 | R$ 366,970 | R$ 313,259 | R$ 0.075 | R$ 3,310,457 |
| Trading Gains | R$ 2,264,809 | -R$ 1,381,849 | R$ 2,819,970 | R$ 0.671 | R$ 12,566,475 |
| CRI Interest | R$ 1,870,263 | R$ 3,588,367 | R$ 2,105,810 | R$ 0.501 | R$ 30,664,605 |
| CRI Inflation Adjustment | R$ 310,705 | R$ 277,977 | R$ 333,533 | R$ 0.079 | R$ 4,225,475 |
| FII Income | R$ 628,151 | R$ 652,808 | R$ 373,547 | R$ 0.089 | R$ 8,307,110 |
Repo Operations
| CASH EXPENSES | -R$ 462,094 | -R$ 360,873 | -R$ 199,446 | -R$ 0.047 | -R$ 7,548,944 |
|---|---|---|---|---|---|
| Administration Fee | -R$ 267,868 | -R$ 259,367 | -R$ 121,430 | -R$ 0.029 | -R$ 2,909,138 |
| Income Tax Expenses | -R$ 29,624 | -R$ 60,396 | -R$ 57,112 | -R$ 0.014 | -R$ 770,712 |
| Leverage Costs | R$ 0 | R$ 0 | R$ 0 | R$ 0.000 | -R$ 3,019,346 |
| Other Expenses | -R$ 164,601 | -R$ 41,110 | -R$ 20,903 | -R$ 0.005 | -R$ 849,748 |
| RESULT FOR THE PERIOD | R$ 4,829,202 | R$ 3,143,400 | R$ 5,746,672 | R$ 1.368 | R$ 51,493,659 |
| Prior Retained Earnings | R$ 829,327 | R$ 1,458,529 | R$ 401,930 | R$ 0.096 | |
| FINAL RESULT | R$ 5,658,529 | R$ 4,601,930 | R$ 6,148,602 | R$ 1.464 |
TRADI NG, LIQU I DITY & YI ELDS

R$ 9.84 MM
Monthly Volume

469K
Daily Average


R$ 81
Market Price

34,345
R$ 95.38
NAV per Unit

0.85x

P/VP
R$ 1.00
Distribution/Unit August 2026 distribution
15.76%
Annualized DY based on market price
14.73%
12-Month DY based on market price
DISTRIBUTION HISTORY
Active management of real-estate CRIs and portfolio diversification underpin consistency in distributions and value creation.
ASSET MON ITORI NG
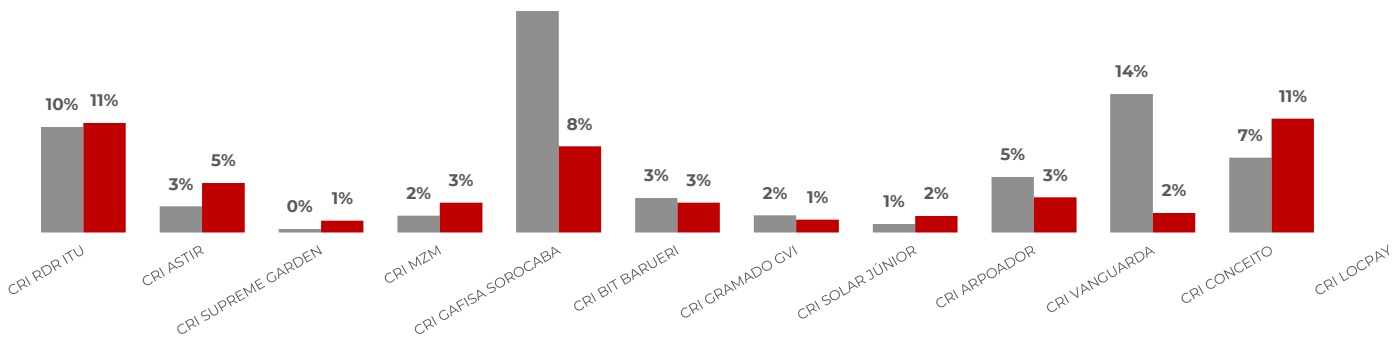
CONSTRUCTION PHYSICAL PROGRESS
RECEIVABLES PORTFOLIO DELINQUENCY
PORTFOLIO SALES LEVEL
ASSET MON ITORI NG
$$ \textsf { S U N O } \Big ( \textsf { A S S E T } \Big ) $$
PORTFOLIO AT PV & INVENTORY
GUARANTEE RATIO STATUS
MAXIMUM RECEIVABLES PORTFOLIO CONCENTRATION
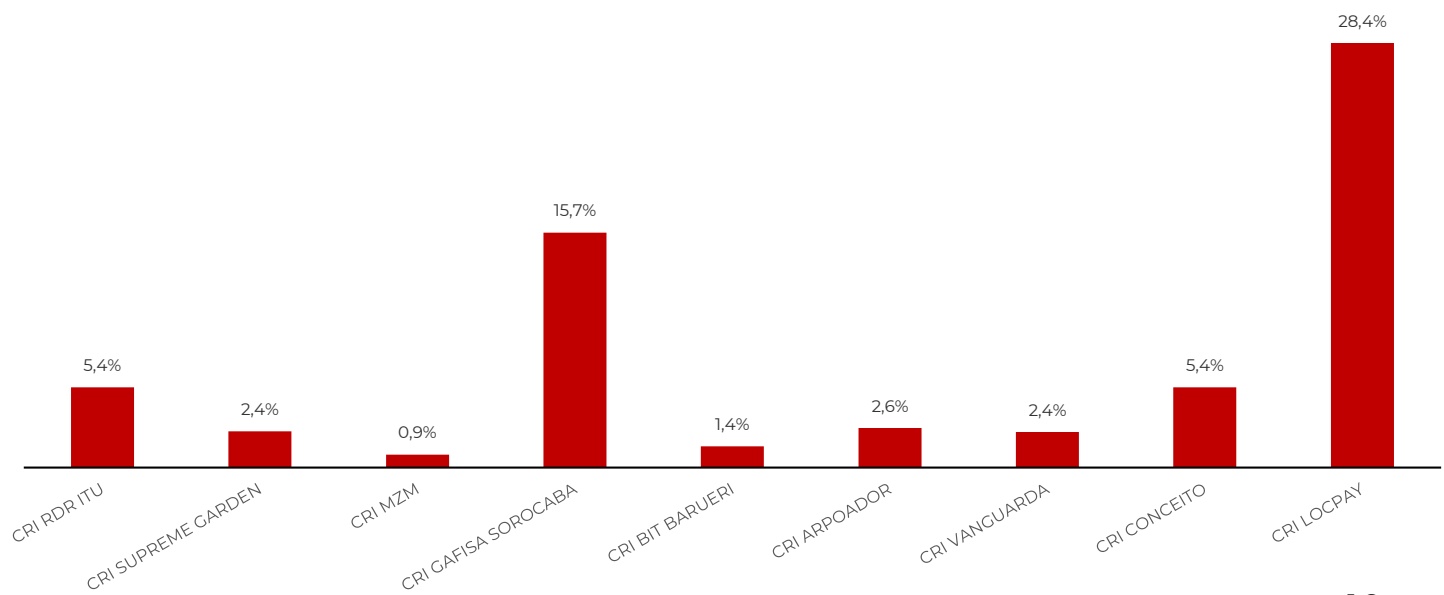
Detail of portfolio/repo transactions (>0.5% of NAV)
| Debtor / Asset | UF | Description | Collateral* | Maturity |
| Residential development in São Bernardo do Campo. Multiple series (I-V). IPCA + CRI MZM SP AF, CF & FR Jun/26 12.95%. Construction in final phase. | ||||
| CRI Supreme Garden | SC | Development in Itajaí. IPCA + 10.50%. Construction 93% complete, 74% sold. | AF, CF & FR | Jun/26 |
| CRI BIT SP Development in Barueri. CDI + 5.50%. Series I-IV. Construction 66%, sales 75%. AF, CF & FR Jul/26 | ||||
| CRI Gafisa Sorocaba | RJ | Gafisa WE development. CDI + 6.00%. Construction 87%, sales 92%. | AF, CF & FR | Sep/26 |
| Aviation - Maintenance center in Guarulhos. IPCA + 5.73%. Atypical BTS (built-to-CRI LATAM SP AF & CF Aug/32 suit). | ||||
| CRI GS Souto | MG | Energy - Distributed-generation small hydro plants (CGHs). IPCA + 11.00%. Prepayment expected. | AF & CF | Apr/26 |
| CRI MRV I Div. MRV corporate. IPCA + 6.50%. Backed by debentures. Clean Feb/29 | ||||
| CRI RDR Itu | SP | Development in Itu. IPCA + 12.00%. Construction 100%. Under recovery. | AF | Matured |
| Healthcare - ONM Health (Opy). IPCA + 10.50%. Hospital PPPs (public-private CRI OPY Health MG AF & CF Aug/31 partnerships). | ||||
| CRI Itabira | MG | Energy - UFV Itabira (solar PV plant). IPCA + 11.00%. Operational. | AF & CF | Dec/38 |
| CRI Ceratti Magna SP Logistics warehouse in Vinhedo. IPCA + 8.50%. Magna and Ceratti contracts. AF, CF & FR May/27 | ||||
| CRI AXS III | Div. | Energy - AXS EnergyTech. IPCA + 11.00%. Series III. | AF & FR | Jul/30 |
| CRI MRV II Div. MRV corporate. IPCA + 6.50%. 2nd series, debentures. Clean Feb/29 | ||||
| CRI Comporte | SP | Corporate - São Paulo transport. CDI + 3.50% | AF & FR | Sep/30 |
| CRI Copagril PR Corporate - Agribusiness cooperative. IPCA + 6.50% AF & FR Jun/31 | ||||
| CRI Pesa/AIZ | PR | Corporate - Heavy machinery. IPCA + 5.5% and 7.0%. Under recovery. | AF, CF & FR | Dec/37 |
| CRI Conceito | MA | Pulverized - Development in São José do Ribamar/MA. CDI + 6.50%. | AF, CF & FR | Oct/29 |
| CRI GF6 | MA | Pulverized - Land subdivision portfolio in Imperatriz/MA. IPCA + 15.00%. | AF, CF & FR | Aug/33 |
| CRI Mahalo | ES | Pulverized - Development in Vila Velha/ES. CDI + 6.00%. | AF, CF & FR | May/30 |
| CRI Oliveira | SP | Corporate, backed by a development in Sorocaba/SP. IPCA + 12.68%. | AF, CF & FR | May/30 |
| CRI Wimo IV | Div. | Pulverized - Senior home equity. IPCA + 8.00%. | AF, CF & FR | Jan/37 |
| CRI LocPay | Div. | Pulverized senior - Assignment of rents. Fixed rate of 23.87% p.a. | CF & FR | Jul/31 |
| CRI Mitre 2025 | SP | Corporate - Upper-middle-income developer in São Paulo/SP. | Clean | Dec/29 |
| CRI Esatas | SP | Contractual - Lease receivables, Campinas/SP airport. IGPM + 8.0%. | AF, CF & FR | Apr/36 |
| CRI Rede Duque | SP | Corporate - Receivables from BR gas stations in SP. IPCA + 8.20%. | AF, CF & FR | Sep/33 |
| CRI Arpoador | ES | Pulverized - Development in Vila Velha/ES. CDI + 6.00%. | AF, CF & FR | Jan/28 |
| CRI Vanguarda | PI | Pulverized - Development in Teresina/PI. INCC + 11%. Under recovery. | AF, CF & FR | Matured |
| Real Estate Fund | ||||
| TGAR11 - Hybrid FII TG Auro. Annualized DY 14.38%. - - | ||||
| SNME11 | - | Hybrid FII managed by Suno Asset. Annualized DY 14.14%. | - | - |
| INOI | - | FII of logistics warehouses in Paraná, managed by Inter Asset. | Subord. | - |
| VRTM11 | - | Multi-strategy FII managed by Fator. | - | - |
| RECD11 | - | Receivables FII managed by Real Estate Capital. | - | - |
| Idees Pompéia | SP | FII for real-estate development in São Paulo/SP | - | - |
AGTs OF TH E MONTH
| Date Asset | Agenda | Resolution | |
|---|---|---|---|
| CRI LocPay | August 4, 2026 | (i) Amend the Remuneration of the CRIs, from the fixed rate of 23.87% per year to the floating rate corresponding to 100% of the DI Rate (CDI), plus a spread of 5.50% per year. (ii) Reflect the new Remuneration and the new calculation methodology in Clause 6.2 of the Securitization Term, including the defined terms “DI Rate” and “Capitalization Period” in Clause 1.1 and amending Clauses 6.2.1 and 6.2.2. | In favor of all. Approved to correct an issuance error. |
| CRI Gafisa | August 12, 2026 | (i) Extend the Maturity Dates of the Commercial Notes and the CRIs, originally scheduled for January 21, 2027 and January 25, 2027, to July 22, 2027 and July 26, 2027, with all other payment terms maintained, upon payment by the Debtor of a premium totaling R$ 2,966,235.93 (Restructuring Fee) within 3 business days of the meeting, by deposit into Operating Collection Account 1, it being established that, if not paid, the amount will be added to the Outstanding Balance of the Commercial Note and. consequently, of the CRI. (ii) Grant an additional period until September 15, 2026 for the Debtor to cure the breaches of non- monetary obligations under item (iii) of the resolutions of the previous meeting: delivery of the Report on Verification and Use of Proceeds, delivery of the Collateral Report, registration of the AFI Agreement, registration of the Fiduciary Assignment Agreement, registration of the AFP Agreement and engagement of the Monitoring Agent. | In favor of all. Approved to extend the transaction due to the construction delays observed. |
| CRI LocPay | August 17, 2026 | (i) Rectify the meeting of August 4, 2026, specifically item (i) of the agenda, which amended the remuneration across the board for all series, establishing that the change to loo% of the DI Rate plus a spread of 5.50% per year applies only to the 3rd and 4th Series, with the fixed remuneration of 23.87% per year of the 1st and 2nd Series remaining unchanged. (ii) Ratify all other items of the meeting of August 4, 2026 not amended by this rectification and ratification. (iii) Amend Clauses 6.2.1 and 6.2.2 and include Clauses 6.2.3, 6.2.4 and 6.2.5 of the Securitization Term, to reflect the two remuneration methodologies (fixed-rate for the 1st and 2nd Series and DI plus spread for the 3rd and 4th Series) and the automatic postponement of payments falling on a non-business day. | In favor of all. Approved to correct the error in the previous amendment, which improperly covered the 1st and 2nd Series. |
| CRI Supreme Garden | August 19, 2026 (clause 9.2 (i) (a)); (b) latest amendment to the Debtor's articles of association; (c) evidence of the use of proceeds from December 2025 to August 19, 2026. (vii) Additional period of up to 90 calendar days, from August 19, 2026, for delivery of the documents in item (vi). | (i) Suspension of the automatic acceleration of the Commercial Note ("NC", clauses 5.7.3 and 8.2 (ii)) and no mandatory redemption of the CRIs (clause 9.4 of the Securitization Term, "TS"), due to the non- replenishment of the Expense Fund after the waiver of the AGT of May 13, 2026, which ended on July 31, 2026. (ii) Additional period of 90 calendar days, from August 19, 2026, to replenish the Expense Fund through the Payment Priority Order (clause 5.8 of the TS) or by contribution from the Debtor up to the Initial Amount (clause 5.7.3 of the NC). (iii) Same suspension and no mandatory redemption with respect to the Interest Fund (clauses 5.8.2 and 8.2 (iii) of the NC), not replenished after the same waiver (July 31, 2026) (iv) Full transfer of the Construction Fund, R$ 235,826.29, to the Interest Fund, and an additional period of up to 90 calendar days, from August 19, 2026, to replenish it through the same priority order or by contribution from the Debtor (clause 5.8.2 of the NC). (v) No declaration of the non-automatic acceleration of the NC (clause 8.3 (iii)) and no mandatory redemption of the CRIs due to the Guarantee Ratio non-compliance not cured as per the AGT of February 24, 2026; period until the occupancy permit (habite-se), expected for November 30, 2026, for extraordinary amortization of the NC and the CRIs, permitted outside a Payment Date, restoring compliance with the Guarantee Ratio (clause 6.3 (ii) of the NC). (vi) No declaration of the non-automatic acceleration of the NC (clause 8.3 (iii) of the Issuance Instrument of February 18, 2022) for failure to deliver: (a) 2024 income tax returns of the Guarantors | In favor of all. Suspending the acceleration preserves more value than mandatory redemption, with short 90-day periods and extraordinary amortization tied to the occupancy permit expected for November 30,2026. |
| CRI AIZ | August 27, 2026 schedules of the CCBs and the CRIs. Notice. | (a) Engagement of the law firm Cescon, Barrieu, Flesch e Barreto Advogados as legal advisor in the sale of the property registered under No. 107.140 (former registrations 83.527, 83.528, 83.529 and 83.530) at the 1st Real Estate Registry Office of São José dos Pinhais/PR ("Warehouse"), a sale approved at the AGT of January 14, 2025, under the terms of the proposal in Annex Il to the supporting material (b) New extension of the deadline to October 30, 2026 for completion of the Warehouse sale, deemed completed upon execution of the documents by all parties, registration at the competent Réal Estate Registry and receipt of the sale proceeds by the securitization company. A new formal acquisition proposal received within this period obliges the Issuer to call a new meeting. (c) Ratification of the new payment terms approved in items (g), (i), (m) and (n) of the AGT of December 24, 2025, with their effectiveness remaining conditional on the sale of the Warehouse by October 30, 2026. The sale of the Warehouse is the main (d) Call of a new meeting within 60 calendar days from October 30, 2026 to resolve on the new payment (e) Contribution by the CRI Holders (clauses 11.3 and 11.4 (b) of the Securitization Term), due to insufficient funds in the Segregated Estate, to cover outstanding Issuance expenses and those faíling due over the next 6 months, incuding legal advisor fees. Voluntary and optional, proportional to each Holder's position, requested by Notice to the Market; an insufficient contribution authorizes a supplementary call by a new | In favor of all. Matters approved by 99.85% of the outstanding CRIs present, with 0.15% of votes against and no abstentions, with attendance of 58.30% of the outstanding CRIs. source of credit recovery, and the engagement of the legal advisor and the extension to October 30, 2026 are necessary to complete it. |
SNAG11
SNFZ11

SNCIM1

SNEL11
SNID11
SNME11

SNFF11

SUNO PREV
FIC FIA
SUNO GLOBAL EQUITIES
LEARN MORE


IG SUNO ASSET
YT SUNO ASSET

SNCI11 - SITE SUNO ASSET

What is SNCI11?
Suno Asset’s Real Estate Credit FII (CRI-focused fund) that invests in real-estate receivables, focusing on development, land subdivision, home equity and energy, seeking return and diversification.
What is the fund’s objective?
To generate predictable, low-volatility monthly income, with diversified investments in CRIs — residential development, land subdivisions, energy and corporate credit.
Are distributions taxed?
For individuals, distributions are exempt from Brazilian income tax, under FII legislation (Law No. 8,668/1993).
What is the risk profile?
Moderate (middle-risk), with 39 diversified CRIs, weighted rating A3, average LTV of 61.41% and active management with continuous monitoring of credits and real collateral.
Where are official reports available?
At suno.com.br/asset/fundos/snci11
Where does the fund invest?
Mainly in CRIs (≈53% IPCA, ≈21% CDI), FIIs (≈10%), repos and cash, diversifying across development, energy and healthcare.
Are the units liquid?
Yes. Traded on B3 (SNCI11), with average volume of R$ 0.47 MM/day and more than 34.3 thousand unitholders.
How do distributions work?
Monthly payments. In August 2026: R$ 1.00/unit, annualized DY of 14.73%. Guidance: R$ 1.00 to R$ 1.10 in 3Q26.
What does P/VP mean?
Market price / net asset value. SNCI11 trades at 0.85x, a ~15% discount to NAV.
How are the assets managed?
Active origination in the real estate market, rigorous credit analysis and continuous monitoring of real collateral and construction.
NOTICE / DISCLAIMER SUNO(ASSET)
This document is a free English translation of the management report (Relatório Gerencial) of Suno Recebíveis Imobiliários Fundo de Investimento Imobiliário (SNCI11), prepared solely for the convenience of readers who do not read Portuguese. The Portuguese version is the sole official version, is the one filed with the Brazilian Securities and Exchange Commission (Comissão de Valores Mobiliários – CVM) and disclosed under applicable Brazilian regulation and ANBIMA self-regulation, and prevails over this translation in the event of any divergence, omission or doubt as to interpretation. It does not replace or amend the Portuguese version, the Fund’s bylaws (regulamento) or any other document of the Fund.
All figures refer to the same reference date as the Portuguese version and are stated in Brazilian reais (R$), the Fund’s functional currency, in which its assets, liabilities and results are recorded and reported to CVM and ANBIMA. Suno Asset assumes no obligation to update this translation.
This document is informational only and does not constitute an offer, solicitation, advertisement or recommendation to buy, sell or subscribe for any security, nor legal, tax or investment advice. SNCI11 is a Brazilian real estate investment fund (Fundo de Investimento Imobiliário – FII), regulated and supervised by CVM, registered for public distribution and admitted to trading exclusively in Brazil, on B3 S.A. – Brasil, Bolsa, Balcão. It is not registered for offer or distribution in any other jurisdiction.
This document is not directed at any person in any jurisdiction where its distribution or use would be contrary to applicable law or would require any registration or authorisation not already obtained. Readers access it on their own initiative and are responsible for observing the rules applicable in their own jurisdiction, including tax and exchange control rules.
Estimates, projections and distribution guidance herein reflect the current judgement of Suno Asset as at the date of disclosure and are subject to change without notice. They are not free from error, offer no assurance that the scenarios described will occur, and do not constitute a promise or guarantee of return, of any future distribution or of capital preservation.
Investment funds are not guaranteed by the fund’s administrator, by the portfolio manager, by any insurance mechanism or by the Brazilian credit guarantee fund (Fundo Garantidor de Créditos in Portuguese, or “FGC”). Past performance is not a guarantee of future results. Investors are advised to carefully read the Fund’s prospectus and bylaws (regulamento) before investing. Investors must be prepared to accept the risks inherent to the various markets in which investment funds operate and, consequently, possible fluctuations in the invested capital. The Administrator is not liable for any errors or omissions in this material, nor for the use of the information contained herein. In addition, the Administrator is not liable for investors’ decisions regarding the matters addressed in this material, nor for the acts or facts of professionals and specialists consulted by the investor.
This material does not relate to the specific investment objectives, financial situation or particular needs of any specific recipient and should not be relied upon as the sole source of information in the investor’s decision-making process. Before deciding, the investor should carry out — preferably with the assistance of a duly qualified professional — a careful assessment of the product and its respective risks against his or her personal objectives and risk tolerance (suitability). The Portuguese version of this report and the Fund’s other official documents are available at https://www.suno.com.br/asset/fundos/snci11.
This report uses terms, acronyms and indices specific to the Brazilian market. Brazilian acronyms are kept as in the original report; the key concepts are explained below.
FII: Fundo de Investimento Imobiliário – Brazilian real-estate investment fund, listed on B3 and regulated by CVM. Distributions to individual investors may be exempt from income tax, subject to the conditions set in Brazilian tax law.
CRI: Certificado de Recebíveis Imobiliários – real-estate receivable certificate; a securitized fixed-income instrument backed by propertyrelated credits, issued by a securitization company.
CCB / Commercial Note (NC): Cédula de Crédito Bancário (bank credit note) and Nota Comercial – debt instruments commonly used as the underlying credit of a CRI.
Securitization company (securitizadora) / Securitization Term: the CRI issuer and the deed (Termo de Securitização) that governs each issuance, its series, payment waterfall and covenants.
Segregated Estate (patrimônio separado): the ring-fenced pool of assets and obligations of a given CRI issuance, insulated from the issuer’s other deals.
Senior / subordinated series: CRI tranches with different payment priority; subordinated series absorb losses before senior series.
AGT: Assembleia Geral de Titulares – general meeting of CRI holders, where waivers, restructurings and other deal resolutions are voted.
Administrator / Manager: under CVM rules, the administrator (administradora) is responsible for the fund’s fiduciary administration, accounting and asset marking; the manager (gestora, Suno Asset) makes the investment decisions.
IPCA: Brazil’s official consumer-price inflation index (IBGE).
IGP-M (IGPM): general market price index (FGV), widely used to adjust rents and contracts.
INCC: national construction-cost index, used to adjust contracts for properties under construction.
CDI / DI Rate: Brazilian interbank deposit rate; the main floating-rate benchmark, closely tracking the Selic.
Selic / Copom: the Central Bank of Brazil’s policy interest rate, set by its Monetary Policy Committee (Copom).
Fixed-rate (pré / prefixado): remuneration set as a fixed annual rate, not linked to an index.
B3 / CETIP code: B3 S.A. – Brasil, Bolsa, Balcão is the Brazilian exchange; the CETIP code identifies a security registered in B3’s OTC registry. IFIX: B3’s benchmark index of listed Brazilian real-estate funds.
Paper FIIs (FIIs de papel): FIIs that invest mainly in real-estate credit (CRIs), as opposed to physical property.
NAV / PL: net asset value (patrimônio líquido, PL). “% of NAV” corresponds to “% do PL” in the Portuguese report; NAV per unit (cota patrimonial) is NAV divided by units outstanding.
P/VP: price-to-NAV: the unit’s market price divided by its NAV per unit.
DY (dividend yield): distributions divided by the unit’s market price, annualized or over the last 12 months.
Yield MTM / HTM: MTM: yield implied by the asset’s market marking; HTM: contractual (hold-to-maturity) rate at acquisition.
LTV: loan-to-value: outstanding credit divided by the appraised value of the collateral.
Guarantee Ratio (GR / Razão de Garantia): collateral (receivables and inventory) over the outstanding balance of a CRI, tested against a contractual minimum.
AF / CF / FR / Aval: collateral types: AF – fiduciary lien on property (alienação fiduciária); CF – fiduciary assignment of receivables (cessão fiduciária); FR – reserve fund (fundo de reserva); Aval – personal guarantee by the debtor’s shareholders or group companies.
Profile: Contr. / Pulv. / Corp.: contractual (credit backed by a specific lease or contract), pulverized (granular pool of many individual buyers’ receivables) and corporate (credit risk of a company).
Development (incorporação) / Land subdivision (loteamento): real-estate development of units for sale; subdivision of land into lots sold in installments.
Occupancy permit (Habite-se): municipal certificate that a building is complete and fit for occupancy.
Onlending (repasse): transfer of buyers’ balances to bank mortgage financing after completion, which repays the development credit.
Repo (operação compromissada): repurchase agreement; short-term secured funding (passive repo) or lending (active repo) backed by securities.
Acceleration / mandatory redemption: vencimento antecipado (early maturity of the debt upon default) and resgate compulsório (compulsory early redemption of the CRI).
Novation / debt acknowledgment / dation in payment: novação (replacement of an obligation by a new one), confissão de dívida (debt acknowledgment agreement) and dação em pagamento (settlement in kind, e.g., with units).
UF / Div.: Brazilian state (unidade federativa), e.g., SP = São Paulo; Div. = diversified across states.
3Q26 / 2H25: third quarter of 2026 / second half of 2025. R$ MM (or mm): millions of Brazilian reais.
FGC: Fundo Garantidor de Créditos – Brazil’s deposit guarantee fund; it does NOT cover investment funds.