
Relatório gerencial em inglês SNCI11 de junho de 2026
Relatório gerencial em inglês do Suno Recebíveis Imobiliários (SNCI11), fundo imobiliário de papel, referente a junho de 2026, com entrega no FundosNet (B3) em 29/07/2026. No pregão de 03/11/2026, a cota do SNCI11 fechou a R$ 78,77, com P/VP de 0,82 (valor patrimonial de R$ 96,06 por cota no informe mensal de setembro de 2026). O último rendimento foi de R$ 1,00 por cota, com pagamento em out/2026, e o dividend yield dos últimos 12 meses é de 13,96% sobre a cotação de 03/11/2026. O patrimônio líquido era de R$ 403,5 milhões no informe mensal de setembro de 2026. Os indicadores são os mais recentes da base do Kartac, não os do período do documento.
Informações
- CNPJ
- 41.076.710/0001-82
- Tipo
- Outras Informações
- Assunto
- Relatório gerencial em inglês
- Data de referência
- 30/06/2026
- Data de entrega
- 29/07/2026 18:58
- Versão
- 1
- Situação
- (Ativo)
Conteúdo
ASNCH
M A N A G E M E N T R E P O R T
JUNE 2026
ANNUALIZED DY
13.95%
NET ASSETS
CO NTE NTS
- Executive Summary 03
- Manager's Letter 04
- Macro & Real Estate Backdrop 10
- Portfolio Summary 11
- Asset Portfolio 13
- Accounting Information 15
- Trading, Liquidity & Yields 16
- Asset Monitoring 17
- Asset Detail 19
- AGTs 20
- Learn More / FAQ 21
SNCI11 Management Report — June 2026
EXECUTIVE SU M MARY
Manager Suno Gestora de Recursos LTDA Administrator BTG Pactual Serviços Financeiros S.A. Fund Inception October 2021
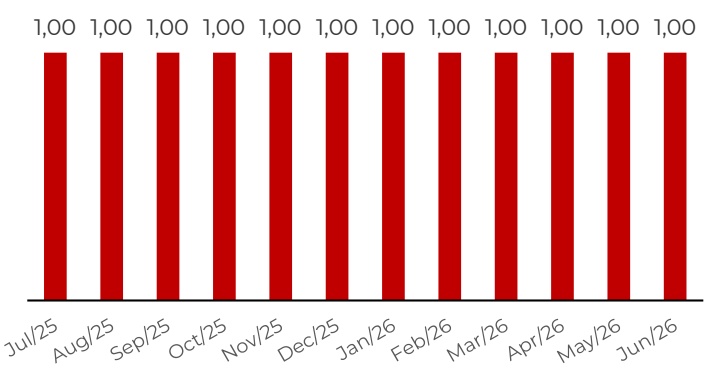
In June, the Fund distributed R$ 1.00 per unit, in line with the guidance of R$ 1.00 to R$ 1.10 for 3Q26. The annualized DY (dividend yield) closed at 13.95% on the market price, with the unit trading at R$ 86.00 (0.89x P/VP, price-to-NAV). The consolidated credit spread was 3.30%, reflecting the easing after the 5.4% peak in 2H25, still at a healthy level for the strategy. Net leverage ended the month negative at -11.85% of net assets (PL), with the Fund as a net creditor in repurchase agreements (repos) of R$ -48.05 MM. Management was active in the unitholders' meetings, notably on resolutions for the Bit Barueri, Gafisa Sorocaba and LocPay CRIs (real-estate receivable certificates). The Fund ended the month with four assets under special treatment: CRI AIZ, CRI Vanguarda, CRI RDR and CRI Solar Junior.
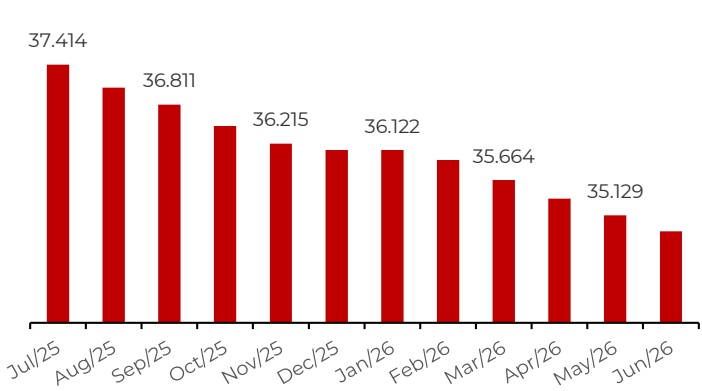
Distribution History (R$)
Number of Unitholders
Dividend Yield (annualized)
Net Assets
Distribution per Unit
13.95%
R$ 405.43 MM
R$ 1.00
Assets in Portfolio 44
P/VP 0.89
Market / NAV per Unit R$ 86.00 / R$ 96.53
Weighted Average LTV 69.60%
Market Value
R$ 361.20 MM
Average Portfolio Yield 16.91%
Accumulated Profit
R$ 0.35
Closing Cash
R$ 31.03 MM
Units outstanding: 4,200,000
Number of Unitholders
34,890
MANAGER'S LETTER
$$ \textsf { S U N O } \Big ( \textsf { A S S E T } \Big ) $$
Dear investor,
We present the Manager's Letter for June 2026, with the aim of sharing an overview of SNCI11's performance, commenting on portfolio activity and future-allocation prospects, and updating holders on asset monitoring and the management team's resolutions at the General Meetings of CRI Holders (AGTs).
Scenario and Performance
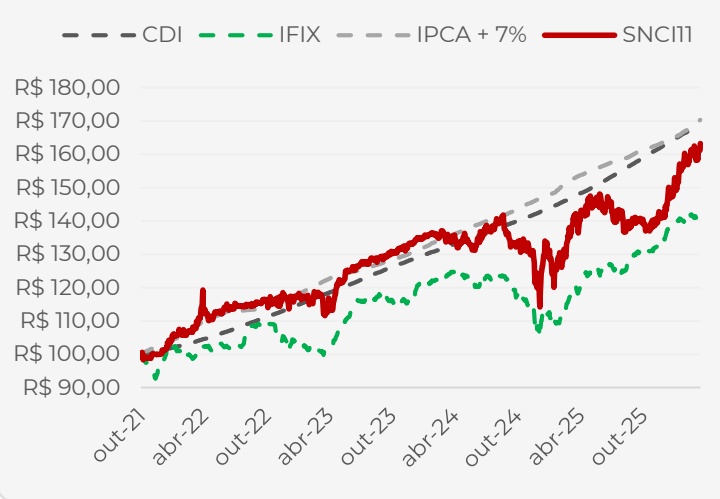
In June, SNCI11 posted an adjusted return of -2.16%, based on the closing unit price, which ended the period at R$ 86.00. During the month, SNCI11 tracked the IFIX (the benchmark index for Brazilian listed real-estate funds), which also declined, returning -1.21%. We believe that global and local macroeconomic events, together with some specific to the real-estate fund (FII) industry, continue to explain the movement seen over the past two months, in which the IFIX was repriced to reflect revised expectations for the Selic (Brazil's policy rate) and the IPCA (Brazil's official inflation index) in Brazil; in the case of paper (credit) funds, we also understand that spread widening, as well as credit events and lower distribution levels at some listed funds, may lie behind the selling pressure that affected FII prices as a whole. Over the past 12 months, however, it is worth recalling that while the Fund achieved an adjusted return of 11.42%, the IFIX returned 9.96%, the IFIX Papel 9.85%, and the average of comparable funds 11.03%, demonstrating SNCI's recovery relative to the industry, driven by the consistency of its distributions and the improvement in the portfolio's spread levels following credit workouts. Despite the improvement in the Fund's pricing, we remain cautious about the recovery movements observed in the AIZ, Solar, Vanguarda and RDR CRIs, which we discuss in detail below. Management has undertaken significant efforts to resolve the credit events in these CRIs, which today amount to 6.91% of the Fund's net assets (PL). We believe these events may explain part of SNCI's slightly lower performance versus the top-performing peers (upper quartile) over the past 12 months (11.42%, versus 11.75% for the most profitable peers).
In addition, the NAV-based return, adjusted for distributions, fell 0.26% in the month, a better performance than the peer-fund average, which declined 0.36%. As a result, net asset value per unit after distribution stood at R$ 96.53. Over the past 24 months, SNCI delivered an adjusted NAV return of 16.61%, slightly below the peer-fund average (16.95%). We highlight that the Fund's assets, especially those in special situations, are duly marked by the Administrator, so that we expect this value to grow as the credit-recovery measures currently underway take effect. Accordingly, the Fund ended the month with a P/VP of 0.89. Average daily trading volume (ADTV) for the month was R$ 512 thousand, below the 12-month average (R$ 664 thousand).
MANAGER'S LETTER
Income Distribution
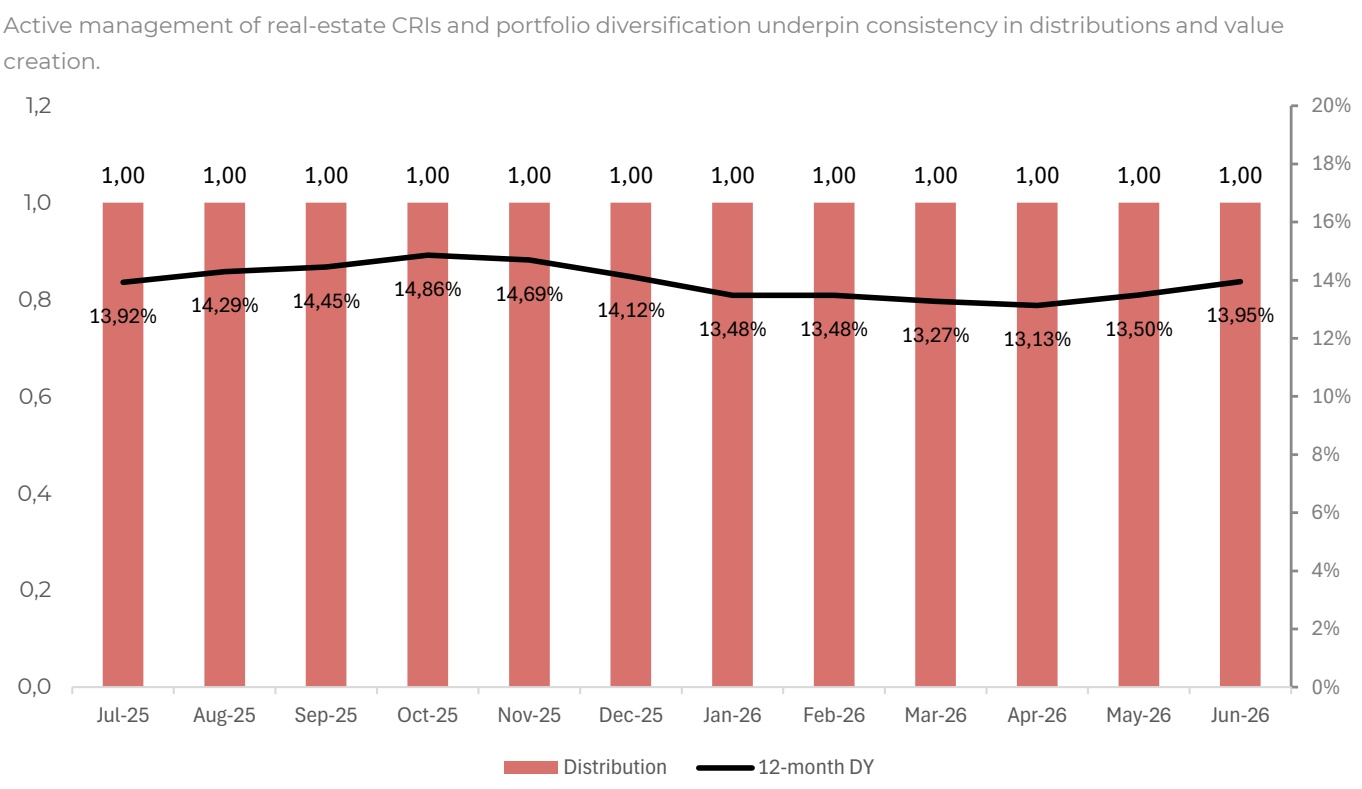
In line with our predictability, the Fund distributed R$ 1.00 per unit in June and announced a new distribution of R$ 1.00 per unit for July, following the published guidance. After the distribution, the Fund ends the period with accumulated earnings of R$ 0.35 per unit.
The distribution guidance is maintained between R$ 1.00 and R$ 1.10 per unit for the third quarter of 2026. We consider this level to remain healthy for SNCI11 while it pursues the credit-recovery measures on the assets in special situations and awaits the maturation of its real-estate developments, notably those of MZM, Supreme Garden, Bit Barueri and Gafisa Sorocaba. We also reinforce the Fund's middle-risk profile and the bias toward smoothing distributions in the interest of predictability for our investors. We will continue to closely monitor the inflation indices (IPCA/INCC — the INCC being Brazil's construction-cost index) and the Selic, which are the benchmarks for the Fund's CRIs. We note that, on June 17, COPOM (the Central Bank's monetary policy committee) cut the Selic by 0.25 pp, to 14.25% p.a., continuing the monetary-easing cycle, which appears to be showing signs of review and a potential pause. We will keep our investors informed of any impacts on the assets' returns and, consequently, on SNCI11's distribution.
Portfolio Management and Leverage
In line with our active-management strategy, we highlight the following transactions in June:
Purchases:
R$ 8.25 million of the Oliveira CRI, at a rate of IPCA + 12.68%, a new proprietary-structured deal to finance the pre-development of a "Minha Casa, Minha Vida" project (Brazil's federal affordable-housing program) in Sorocaba/SP. This is the asset's 1st tranche, which should receive an additional R$ 8 million over the coming months. The deal has its Development Registration (RI) approved and is in the sales-stand preparation phase ahead of launch. Construction is expected to begin in 1Q27 and will be financed by Caixa Econômica Federal (CEF, the state-owned savings bank). The builder has GERIC (Caixa's engineering approval for the development) approved with CEF and has other projects underway in the region. The CRI holds a fiduciary lien (alienação fiduciária) over 85% of the project's units, a senior fiduciary assignment of the receivables from unit sales owed to the builder, and of the reimbursements of the ideal land fractions (FITs) owed by CEF to the builder, both received in accounts under the exclusive control of the securitization company (issuer).
R$ 24 million in Gafisa S.A. shares, during its capital-increase process, representing a liquidity effort to complete construction of the We Sorocaba project (Gafisa Sorocaba CRI). Approximately 60% of this volume has already been sold with no losses incurred by the Fund, within a prior structured transaction. We expect to continue the sales over the coming periods, within the same structured transaction. The sole objective of this strategy is to complete construction of the project backing the CRIs held by the Fund.
MANAGER'S LETTER
R$ 26.5 million in a residential-development FII for a project in São Paulo/SP, in order to provide a warehousing bridge (barriga de aluguel) to the vehicle's end-allocator, which carries good credit risk. The carry on the repo is CDI + 2% (the CDI being Brazil's interbank benchmark rate), and it has a maximum term of one year.
• Sales:
R$ 59.87 million were sold on a temporary basis from the AXS 3, WIMO, WIMO IV, Copagril, Mitre 2025, GF6 and Opy Health CRIs. Approximately R$ 40.32 million have already been repurchased in early July (AXS 3, Mitre 2025, GF6 and Opy Health), while a balance remains to be repurchased over the coming months (WIMO, WIMO IV and Copagril).
• Payoffs:
• A repo of R$ 7.3 million was paid off, at an IRR equivalent to 25% p.a.
As a result, the Fund ended the month with cash equivalent to 7.65% of net assets (R$ 31.03 million), which places net leverage at -7.12% of net assets, corresponding to R$ 28.85 million in active repos i.e., with SNCI as a net creditor. Part of these repos should be unwound during July, driven by potential new allocations.
Future Allocation Outlook (Pipeline)
Attentive to portfolio recycling and diversification, SNCI11 currently holds some future-allocation expectations, which may or may not materialize within the indicated timeframes and amounts, as follows:
• July 2026
Up to R$ 2 million in a new series of the LocPay Senior CRI, at an expected rate of CDI + 5.50%.
• August 2026
Up to R$ 10 million in a new investment in a construction-completion CRI for a developer in Vila Velha/ES, at an expected rate of CDI + 6.00%;
Up to R$ 9 million in a new investment in a land-acquisition CRI for development, at an expected rate of IPCA + 12.68%, plus an equity kicker, in the final structuring phase;
• Possible investments to complete construction in the Bit Barueri and MZM deals.
MANAGER'S LETTER
Asset Monitoring and Resolutions at AGTs
We ended June with four assets under special treatment due to defaults/restructurings: CRI AIZ, CRI Vanguarda, CRI RDR and CRI Solar Junior. The information addressed here reflects Management's visibility as of the publication date of this report, i.e., through mid-July 2026.
Regarding the Vanguarda CRIs, the notes were accelerated following an AGT on August 18, 2025, after sales diversions by the builder were identified. As a result, the CRIs are officially in recovery. Today, all units of both projects (Jonathan Nunes and Dom Severino), except for those duly swapped at the start of the deal and those paid off by formal buyers, are already registered in the name of the securitization company. Consequently, any third-party buyers not suited to the deal's structure will have to litigate against the securitization company, which is prepared to defend the fiduciary right to the buildings' units. As for the transfer of the receivables portfolios, both projects are currently pending their occupancy permit ("Habite-se"). Dom Severino has just under 80% of construction completed, and the securitization company is assessing, together with other local builders, a transfer of the works to complete the project — a far-from-simple process. Until then, the construction site will remain closed. At Jonathan Nunes, the project is finished, but due to documentary pending items on the part of Vanguarda Construtora, it was not possible to register the building's occupancy permit. The securitization company already has a lawsuit underway to obtain the document — and is assessing replacing the technical officer to issue the "Habite-se" through the usual channels — since Vanguarda has already been removed from the units' title records, but this is expected to still take a few months through that route. Although that route remains possible, we made progress in obtaining quotes from builders willing to finish the works and issue the occupancy permit for both projects. With this visibility, considering the remaining construction liability and receivables plus inventory of around R$ 52 million, we have an updated expectation close to 60% of cost. The decline in this indicator is due mainly to the inclusion of the costs of resuming construction, issuing the occupancy permit and legal expenses to be incurred in the deal. There will be a need to contribute funds to the segregated estate (patrimônio separado) to cover the expenses required to release the portfolio transfer, such contributions being proportional to each investor's stake in the CRI. SNCI's position represents less than 4% of the total issued, so any contribution needs will be residual and will not harm the Fund's distribution. We consider this necessary for the proper recovery of the asset. The note's unit price (PU) is already duly marked close to cost in the Fund (R$ 1,061.00). Finally, measures against Vanguarda Engenharia LTDA are under review for the events flagged by the audit. We will update investors on the steps and successes of the recovery.
In the case of the AIZ CRI, we held a Meeting on December 24, 2025 to define the final restructuring of the deal.
MANAGER'S LETTER
As a result, the assets are once again performing (albeit with grace periods underway) and haircuts were applied to series 301 and 302 following the negotiated sale of the main collateral property. The price offered for the property was below the forced-sale value in the appraisal and, given the more than 12 months between the start of the sale process and receipt of the offer, investors decided to accept the agreed terms, granting a haircut of approximately 20% on CRI 301 (which had the fiduciary lien over the properties as security) and 48% on CRI 302 (which had no collateral); CRI 301 will be fully redeemed from the property sale, already net of the 20% haircut, and CRI 302 will be extended for 10 years, with monthly interest from January 2027 and a rate of CDI + 3.50% p.a., plus the addition of part of the collateral previously exclusive to series 301 and not yet sold (approximately R$ 10 million in market value). As a result, we expect a negative impact of R$ 0.22/unit on the Fund's cash result, despite a positive impact of R$ 0.26 on the unit's net asset value. Given the difficult negotiation and market for the property, we believe the restructuring efforts may be offset by high recoverability, which should materialize over the second half of 2026. Nonetheless, a new AGT was held on February 27, 2026 and another on May 29, 2026, given the delays in the property sale, extending the expected completion of the deal to August 2026. We will keep investors updated on this progress and any impacts on the recoverability indicated.
Regarding the RDR CRI, we decided not to extend the deal's term at maturity, since construction was already duly completed, with the CRIs related to the deal maturing on August 20, 2025. Accordingly, prioritizing transparency to investors, the asset is currently in recovery and duly marked at cost in the Fund's NAV per unit, considering the recoveries already obtained. We understand that, in doing so, we have taken a conservative stance regarding the recoverability of the credits. We are working daily together with the securitization company and the deal's legal advisor to strengthen our prospects of collecting the portfolio (~R$ 10 million) over the coming months, in addition to working on the sale of the additional collateral. We will disclose any action taken provided that we understand, together with the legal advisors, that it will not harm the Fund in the credit-recovery work. On this front, in March we concluded a Meeting that allowed the dation in payment (dação em pagamento) of part of the project's units, as well as the restructuring of part of the CRI into separate debts for each partner and for the company itself. In addition, upon the full execution of these actions, the regularization of the CRI's pending items, and the final audit of the receivables portfolio, we will grant a haircut on the CRIs' updated outstanding balance, a measure necessary within the credit restructuring. It is important to state that this haircut will not cause new NAV or cash losses to SNCI (which already marks the asset at cost) and which remains focused on the credit-recovery measures.
MANAGER'S LETTER
In June, we obtained the recovery of R$ 102 thousand owed on the asset, reducing the cost price to R$ 18.6 million (4.56% of SNCI11's net assets). As an update, we already have a ninth recovery round scheduled for July 27, in which approximately R$ 1.7 million will be amortized, lowering SNCI's cost price in the deal to R$ 16.9 million (4.17% of SNCI11's net assets). In addition, in May we executed the assignment of 3 debt acknowledgments that will represent a novation of part of the receivables from the CRIs, which will amortize and restructure — for extended collection agreed with the company's partners — the amount of R$ 13.5 million, reducing SNCI11's effective default rate in the deal to 0.84%, to be confirmed from July 2026. We believe this advance will be an essential achievement in the credit recovery, allowing a relevant part of the portfolio to return to profitability and a meaningful reduction in the Fund's current delinquency. For the record, this development will not affect the Fund's distribution level, since it was already a deal with interest capitalization and therefore no impact on monthly receivables. Accordingly, we reaffirm the distribution guidance of between R$ 1.00 and R$ 1.10 per unit for the third quarter of 2026.
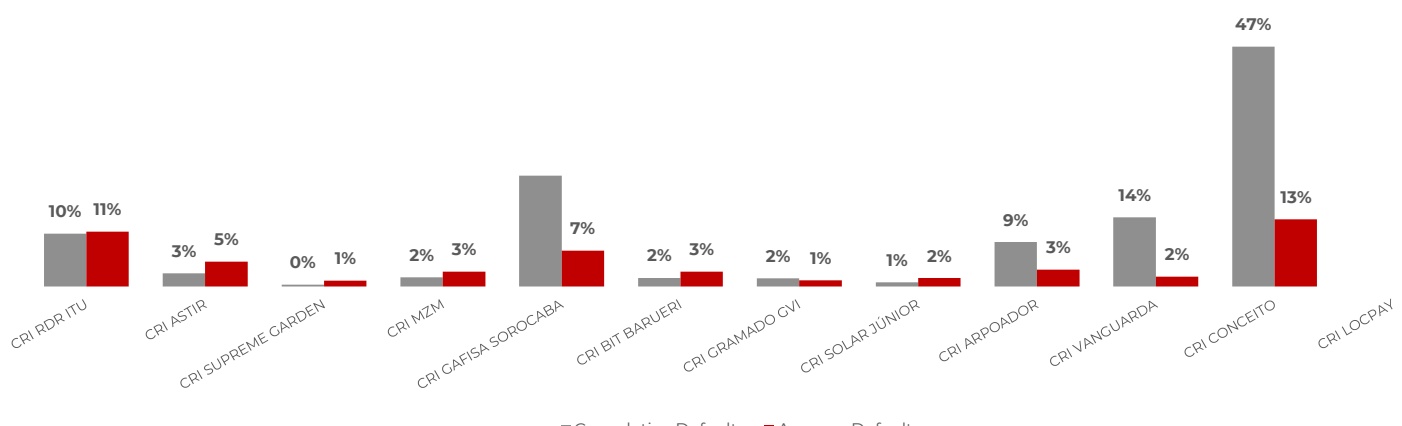
Finally, regarding the Solar Junior CRI, representing 0.1% of SNCI's net assets, the CRI had its maturity and default confirmed on November 21, 2025, with the securitization company ordering the start of the operational and legal work to recover the credits. We are still gathering more information from the securitization company, the trustee and the majority investors, and at this point it is not yet possible to estimate a precise recoverability, even though the securitization company's monitoring report estimates a Guarantee Ratio above 100% considering portfolio and inventory. Even so, the Management team remains confident about resolving the credit event, aware that any defaults or haircuts have a very low potential to impact SNCI11, given its residual position in the asset.
With respect to the formal resolutions at AGTs, we actively participated in the following discussions:
Bit Barueri CRI: Together with the other investors in the deal, we approved the change to the minimum balance of the Interest Reserve to adjust the deal at this time, as well as a waiver conditioned on a new deadline for the debtor to present certain documents and financial statements, understanding that the occupancy permit should be obtained within the coming months, initiating the CRI-repayment process.
Gafisa Sorocaba CRI: We approved the capitalization of the CRI's interest until maturity, with a cash sweep starting from the project's occupancy permit ("Habite-se"), expected in October 2026.
LocPay CRI: We approved the issuance of new series for the deal, which had already had its first R$ 5 million paid in. The second series maintains the subordination but carries a cost of CDI + 5.50% per year. In addition, we revised the eligibility and framing criteria as the deal gained maturity. We included a mandatory buyback clause for defaulted receivables in cases where the minimum 20% subordination is absent.
MANAGER'S LETTER
Additional Considerations
As we closed June 2026, the macro environment remained shaped by the combination of domestic interest rates at a restrictive level, inflation running above the top of the target range, and geopolitical uncertainties which — despite initial signs of a possible easing over the course of the month — have not yet produced lasting relief in the variables that matter most to the FII market: the future interest-rate curve and the local investor's risk appetite.
On the monetary front, COPOM delivered its third consecutive 0.25 pp cut in June, bringing the Selic to 14.25% per year — a decision the market viewed as dovish given the inflationary deterioration acknowledged by the Central Bank itself in its latest Minutes. The IPCA accumulated for year-end came to be projected at 5.11% by the Focus survey (the Central Bank's weekly market-expectations survey), a significant upward revision relative to the start of 2026. This repositioning of expectations is the main source of pressure on the secondary FII market: the repricing of the IFIX, which fell around 1.2% in the month, directly reflects the adjustment of the discount rates applied to the funds' future cash flows, with a more pronounced impact on the longer-duration segments, such as corporate office funds and development funds.
In the real-estate sector, the message from the ABRAINC Summit (ABRAINC being Brazil's association of real-estate developers), held at the end of June, was direct: contrary to the expectations formed at the end of 2025, development executives no longer convey the same optimism about near-term interest-rate cuts, acknowledging that credit will remain restrictive for longer than initially anticipated. For development transactions underway, this scenario translates into a more subdued sales pace, greater reliance on the developers' own capital during the construction phases, and additional pressure on the projects' cash. These are variables that SNCI11 continuously tracks in monitoring the portfolio's transactions.
On the construction-cost front, the INCC continues to run above the IPCA, feeding back into the pressure on the projects' economic viability. The average rates charged by banks on SBPE housing loans (SBPE being Brazil's savings-funded mortgage system) remain between 12% and 14% per year on top of the index, which narrows the universe of buyers eligible for conventional bank financing and heightens the difficulties of the "bank release" (desligamento bancário) in real-estate deals where the project is already completed, delaying the transfer of portfolios and the repayment of debts by the projects and developers.
In the paper-FII market, the credit events and spread widening of the previous months continued to affect the perception of the segment as a whole. The absence of a quick resolution for the stress situations that emerged in the recent cycle contributes to the market demanding an additional premium on higher-risk real-estate credit assets, regardless of their intrinsic quality — a contagion phenomenon which, despite its negative short-term effects on SNCI11's P/VP, reinforces the value of the origination discipline that guides the fund's management.
MANAGER'S LETTER
For SNCI11, the combination of a Selic rate still at a restrictive level — even after the recent cuts inflation revised upward and expensive credit preserves the carry of the portfolio's index-linked positions, while at the same time requiring rigorous monitoring of the projects' operational and commercial performance, as well as highly judicious decision-making regarding investments in new projects. Management continues to selectively assess new origination opportunities, keeping as central parameters a robust collateral structure, the alignment of the LTV to the risk of each transaction, and the demonstrated capacity of the debtors and of the assigned financial flows to service the debt in an environment of still-elevated cost of capital.
Sincerely,
Management Team, SUNO ASSET.
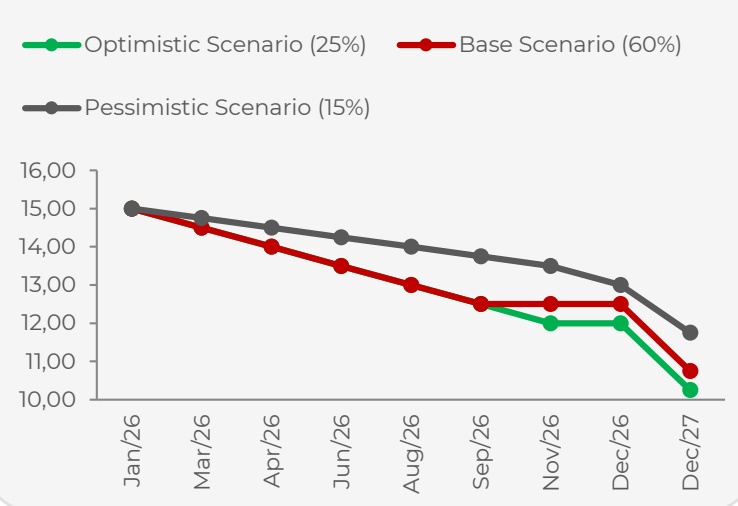
SCENARIO
| Selic | 14.25% |
|---|---|
| IPCA (2026e) | 4.64% |
| Exchange Rate (R$/USD) | R$ 5.18 |
| Brazil GDP (2026e) | 2.0% |
| Unemployment (2026e) | 5.6% |
| Gross Debt (% GDP) | 81.1% |
Performance vs. Benchmarks
PORTFOLIO SU M MARY
Number of Assets in Portfolio 44
Average Leverage Cost CDI + 0.97%
P/VP 0.89
Weighted Portfolio Duration 1.35
Average FII Yield 14.99%
Average CRI Yield (All-In) 17.99%
Net Leverage -11.85% of NAV
Repo Volume R$ -48.05 MM
Avg. CRI Rate (IPCA+) IPCA + 11.08%
Avg. CRI Rate (IGP-M+) IGPM + 8.50%
Avg. CRI Rate (INCC+) INCC + 0.00%
Avg. CRI Rate (CDI+) CDI + 5.72%
PORTFOLIO TOP SECTORS
| Sector | % of NAV |
|---|---|
| Development | 49.9% |
| Energy | 5.9% |
| FIIs | 9.2% |
| Repos | 4.4% |
| Industrial | 6.2% |
| Healthcare | 0.0% |
| Cash | 7.7% |
| Land subdivision | 1.2% |
| Aviation | 2.0% |
| Others | 13.5% |
EXPOSURE BY INDEX (% of NAV)
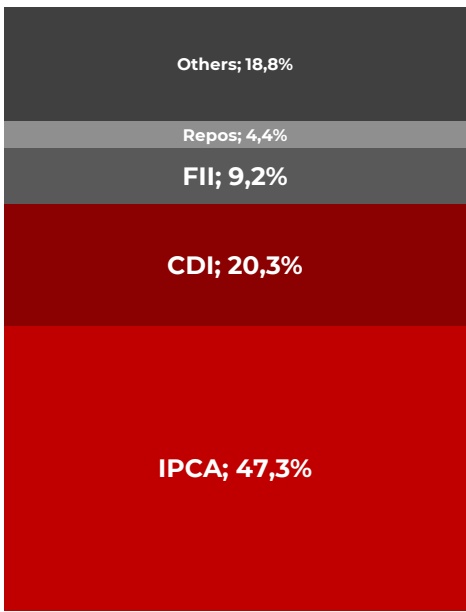
CDI; 20,3%
IPCA; 47,3%
CONSOLIDATED CREDIT SPREAD
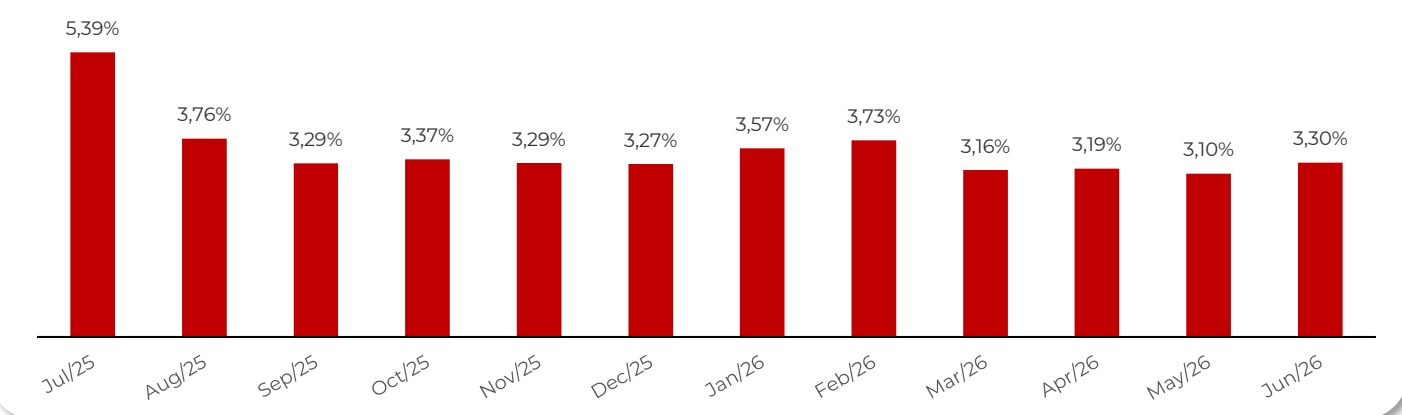
PORTFOLIO SU M MARY
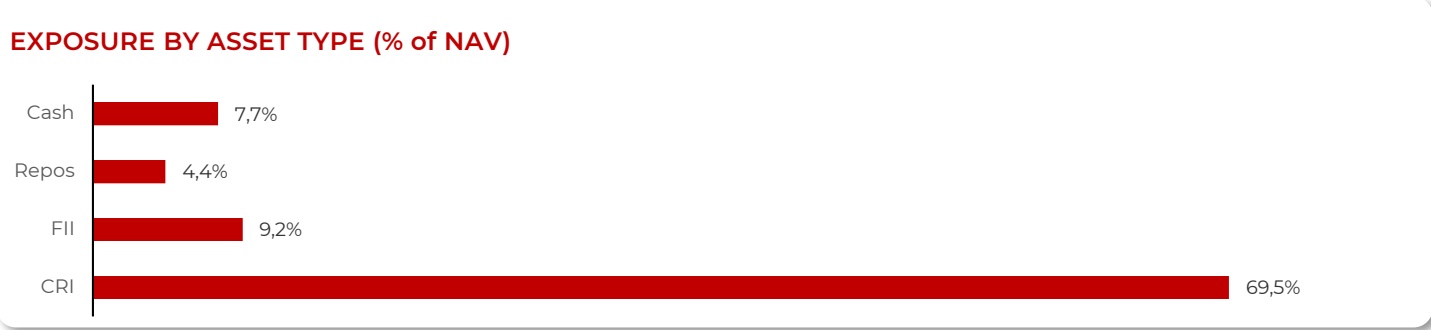
EXPOSURE BY RISK PROFILE (% of NAV)
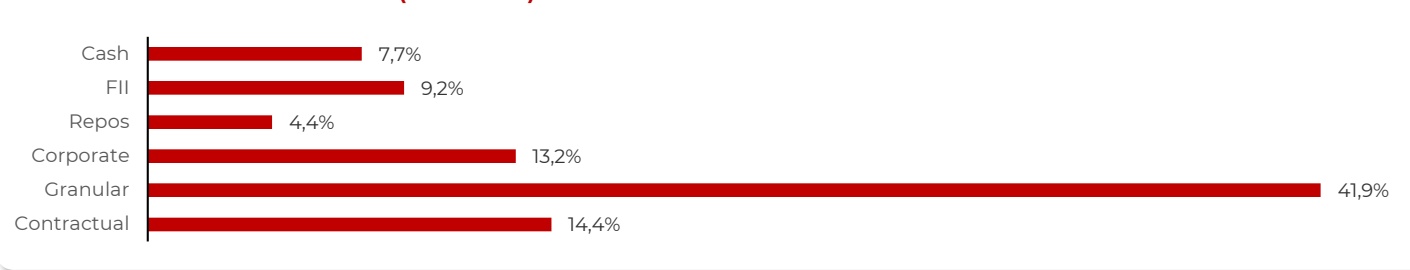
EXPOSURE BY RATING (% of NAV)
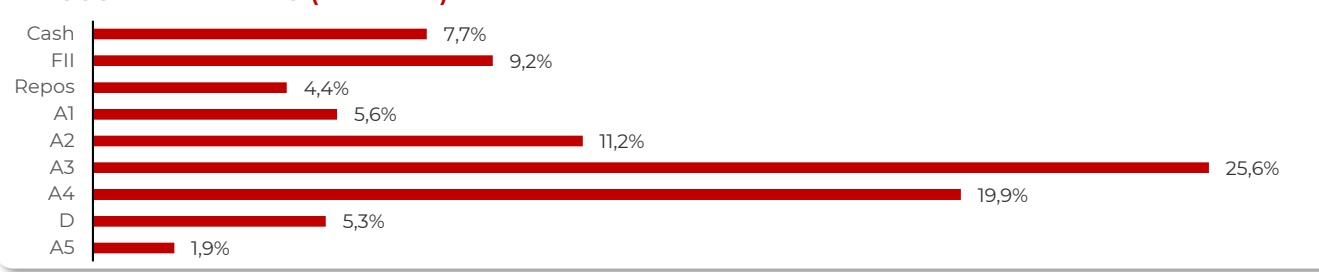
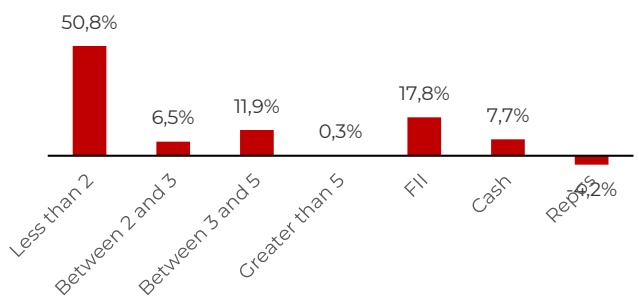
EXPOSURE BY DURATION (% of NAV)
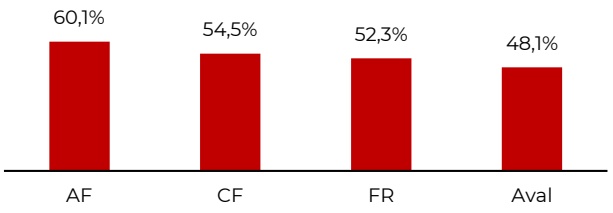
CRI EXPOSURE BY COLLATERAL (% of CRIs)
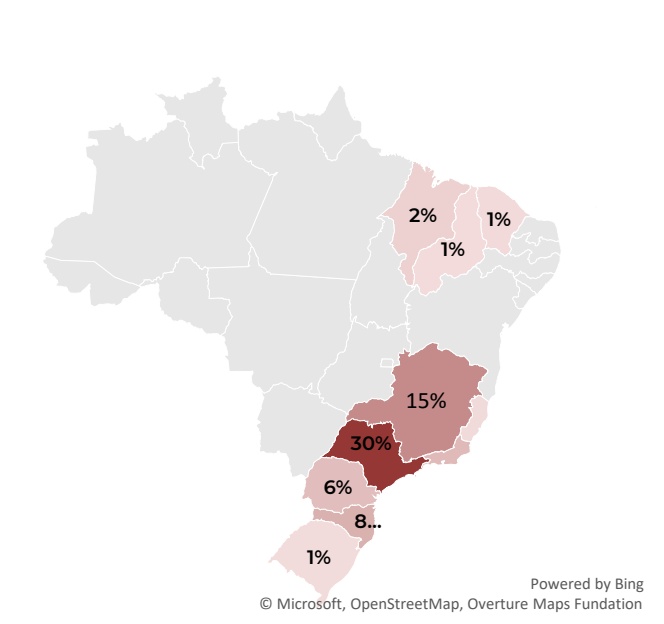
EXPOSURE BY LOCATION
ASSET PORTFOLIO
CRI and Asset Portfolio — June 2026
| Asset | Profile | CETIP Code | Sector | Rtg | Idx | Yield MTM | Yield HTM | Dur. | N%AV | LTV |
|---|---|---|---|---|---|---|---|---|---|---|
| CRI SUPREME GARDEN | Gran. | 22B0338247 | Dev. | A4 | IPCA | 13.82% | 10.50% | 0.31 | 7.38% | 65% |
| CRI GAFISA SOROCABA (new) | Gran. | 25L3104624 | Dev. | A3 | CDI | 6.00% | 6.00% | 0.32 | 6.80% | 90% |
| CRI MRV | Corp. | 21D0001232 | Dev. | A3 | IPCA | 11.21% | 5.43% | 3.41 | 5.57% | - |
| CRI CERATTI MAGNA | Contr. | 22E0120555 | Industrial | A1 | IPCA | 11.74% | 8.50% | 0.85 | 4.66% | 60% |
| CRI ITABIRA | Contr. | 23L2160618 | Energy | A2 | IPCA | 11.83% | 11.00% | 4.21 | 4.30% | 95% |
| CRI BIT Série 4 | Gran. | 22J2609555 | Dev. | A3 | CDI | 5.50% | 5.50% | 0.31 | 3.18% | 60% |
| CRI MZM V | Gran. | 22I1466175 | Dev. | A4 | IPCA | 13.51% | 12.95% | 0.74 | 3.05% | 70% |
| CRI RDR ITU | Gran. | 21K0660418 | Dev. | D | IPCA | 12.00% | 12.00% | 0.00 | 2.81% | 80% |
| CRI MRV II | Corp. | 22B0006022 | Dev. | A3 | IPCA | 12.13% | 6.50% | 1.98 | 2.69% | - |
| CRI MZM II | Gran. | 22I1466133 | Dev. | A4 | IPCA | 14.56% | 12.95% | 0.74 | 2.42% | 70% |
| CRI MZM III | Gran. | 22I1466156 | Dev. | A4 | IPCA | 0.00% | 12.95% | 0.74 | 2.11% | 70% |
| CRI COMPORTE | Corp. | 23I1270600 | Transport | A2 | CDI | 3.54% | 3.80% | 1.89 | 2.10% | 60% |
| CRI OLIVEIRA | Corp. | 26E4609469 | Dev. | A4 | IPCA | 12.93% | 12.68% | 2.49 | 2.04% | - |
| CRI LATAM | Contr. | 21C0818332 | Aviation | A2 | IPCA | 9.37% | 4.50% | 2.70 | 2.03% | 45% |
| CRI BIT Série 3 | Gran. | 22J2609554 | Dev. | A3 | CDI | 6.03% | 5.50% | 0.31 | 2.00% | 60% |
| CRI BIT | Gran. | 22J1411295 | Dev. | A3 | CDI | 5.50% | 5.50% | 0.31 | 1.83% | 60% |
| CRI MZM | Gran. | 22I1465810 | Dev. | A4 | IPCA | 15.68% | 12.95% | 0.74 | 1.66% | 70% |
| CRI GS SOUTO | Contr. | 21K0732283 | Energy | A3 | IPCA | 0.00% | 11.13% | 3.29 | 1.57% | 62% |
| CRI PESA / AIZ (Long) | Contr. | 21F0568504 | Industrial | A5 | IPCA | 0.00% | 7.00% | 0.34 | 1.42% | - |
| CRI MAHALO | Gran. | 26D0059264 | Dev. | A2 | CDI | 6.00% | 6.00% | 2.81 | 1.24% | 75% |
| CRI CONCEITO | Gran. | 25J2612796 | Land subd. | A2 | CDI | 6.50% | 6.50% | 2.49 | 1.23% | 46% |
| C 3RI RDR ITU SÉRIE | Gran. | 21K0661041 | Dev. | D | IPCA | 12.00% | 12.00% | 0.00 | 1.03% | 80% |
| CRI LOCPAY (SENIOR) | Gran. | 25H2417003 | Receiv. | A3 | - | 23.79% | 23.87% | 1.72 | 1.00% | - |
| CRI BIT Série 2 | Gran. | 22J1411297 | Dev. | A3 | CDI | 5.50% | 5.50% | 0.31 | 0.93% | 60% |
| CRI SUPREME GARDEN 509 | Gran. | 25F2808184 | Dev. | A4 | IPCA | 9.56% | 10.50% | 0.31 | 0.80% | 65% |
| C 2RI RDR ITU SÉRIE | Gran. | 21K0660445 | Dev. | D | IPCA | 12.00% | 12.00% | 0.00 | 0.75% | 80% |
ASSET PORTFOLIO
CRI and Asset Portfolio — June 2026
| Asset | Profile | CETIP Code | Sector | Rtg | Idx | Yield MTM | Yield HTM | Dur. | N%AV | LTV |
|---|---|---|---|---|---|---|---|---|---|---|
| CRI VANGUARDA | Gran. | 22G1233041 | Dev. | D | INCC | 0.00% | 11.00% | 0.00 | 0.65% | 52% |
| CRI ARPOADOR (SUBORDINATED) | Gran. | 23J2809383 | Dev. | A1 | CDI | 12.00% | 12.00% | 1.32 | 0.51% | 43% |
| CRI ESTOQUE HELBOR | Corp. | 22H1104501 | Dev. | A2 | CDI | 2.71% | 2.30% | 0.62 | 0.32% | 80% |
| CRI GRAMADO GVI | Gran. | 21F0950048 | Fractional | A5 | IPCA | 9.50% | 9.50% | 1.18 | 0.30% | 26% |
| CRI ESATAS | Contr. | 21C0572241 | Infra. | A1 | IGP | 8.50% | 7.56% | 6.93 | 0.29% | 80% |
| REDE DUQUE (Series 443) | Corp. | 21I0855537 | Oil & Gas | A4 | IPCA | 13.36% | 7.25% | 3.14 | 0.22% | 67% |
| REDE DUQUE (Series 444) | Corp. | 21I0855623 | Oil & Gas | A4 | IPCA | 13.41% | 7.25% | 3.13 | 0.22% | 67% |
| CRI Pesa / AIZ (Short) | Contr. | 21F0569265 | Industrial | A5 | IPCA | 0.00% | 5.50% | 0.09 | 0.15% | - |
| CRI ARPOADOR (SENIOR) | Gran. | 23J2266231 | Dev. | A1 | CDI | 4.50% | 4.50% | 1.39 | 0.14% | 43% |
| CRI SOLAR JUNIOR | Gran. | 19K1139245 | Fractional | D | IPCA | 17.42% | 16.64% | 0.00 | 0.09% | 68% |
| FIIs | Sector | Qty | Price | Yield | Yield on Cost | P/VP | N%AV | Ca%sh | Avg. Cost |
|---|---|---|---|---|---|---|---|---|---|
| SNME11 | Hybrid | 3,731,239 | R$ 9.50 | 13.27% | 12.93% | 0.99 | 5.4% | 18.6% | R$ 9.75 |
| INOI | Logistics | 35,000 | R$ 103.81 | 9.15% | 9.49% | 1.03 | 0.9% | - | R$ 100.00 |
| TGAR11 | Hybrid | 164,474 | R$ 88.29 | 16.85% | 12.24% | 0.48 | 1.5% | 0.2% | R$ 121.60 |
| RECD11 | Paper | 400,000 | R$ 10.00 | 15.01% | 15.01% | 0.99 | 0.7% | 8.3% | R$ 10.00 |
| ZAVC11 | Paper | 57,972 | R$ 9.05 | 17.02% | 14.88% | 0.89 | 0.1% | 10.4% | R$ 10.35 |
| VRTM11 | Hybrid | 304,693 | R$ 6.85 | 15.69% | 11.07% | 0.75 | 0.5% | 7.5% | R$ 9.71 |
| Repos | - | - | - | - | - | - | 4.4% | - | - |
| REPURCHASE AGREEMENTS | Profile | CETIP Code | Sector | Idx | Yield HTM | Borrowing Yield | Vol. (MM) |
|---|---|---|---|---|---|---|---|
| CRI Esatas Viracopos | Contr. | 21C0572241 | Infra. | IGP | 8.00% | 8.00% | R$ 8.00 |
| Rede Duque (Series 443) | Corp. | 21I0855537 | Oil & Gas | IPCA | 7.25% | 7.25% | R$ 5.00 |
| Rede Duque (Series 444) | Corp. | 21I0855623 | Oil & Gas | IPCA | 7.25% | 7.25% | R$ 5.00 |
ACCOU NTI NG I N FORMATION
R$ 5.29 M
Distributable Income generated in the month
R$ 1.15
Result/Unit net result in the month
R$ -0.46 M
Expenses fees + operating costs
R$ 1.00 M
Distribution R$ 4.20 MM total distributed
R$ 4.83 M
Net Result R$ 1.15/unit
R$ 1.46 M
Reserve Movement reserve: R$ 0.35/unit
INCOME STATEMENT — JUNE 2026
| APR/26 | MAY/26 | JUN/26 | R$/Unit (M0) | LTM | |
|---|---|---|---|---|---|
| DISTRIBUTABLE INCOME | R$ 5,183,949 | R$ 3,985,839 | R$ 5,291,296 | R$ 1.260 | R$ 59,477,801 |
| Cash Income | R$ 198,329 | R$ 120,138 | R$ 217,369 | R$ 0.052 | R$ 3,062,280 |
| Trading Gains | R$ 418,050 | R$ 575,490 | R$ 2,264,809 | R$ 0.539 | R$ 11,367,333 |
| CRI Interest | R$ 3,122,004 | R$ 1,896,117 | R$ 1,870,263 | R$ 0.445 | R$ 31,049,376 |
| CRI Inflation Adjustment | R$ 708,249 | R$ 665,283 | R$ 310,705 | R$ 0.074 | R$ 5,238,123 |
| FII Result | R$ 737,317 | R$ 728,810 | R$ 628,151 | R$ 0.150 | R$ 8,792,209 |
| CASH EXPENSES | -R$ 629,405 | -R$ 384,961 | -R$ 462,094 | -R$ 0.110 | -R$ 8,596,002 |
|---|---|---|---|---|---|
| Administration Fee | -R$ 266,666 | -R$ 271,643 | -R$ 267,868 | -R$ 0.064 | -R$ 3,045,601 |
| Income Tax Expenses | -R$ 12,115 | -R$ 50,166 | -R$ 29,624 | -R$ 0.007 | -R$ 686,582 |
| Leverage Costs | -R$ 295,671 | -R$ 41,628 | R$ 0 | R$ 0.000 | -R$ 4,018,259 |
| Other Expenses | -R$ 54,953 | -R$ 21,524 | -R$ 164,601 | -R$ 0.039 | -R$ 845,561 |
| RESULT FOR THE PERIOD | R$ 4,554,544 | R$ 3,600,877 | R$ 4,829,202 | R$ 1.150 | R$ 50,881,799 |
| Prior Profit Reserve | R$ 1,073,906 | R$ 1,428,450 | R$ 829,327 | R$ 0.197 | |
| FINAL RESULT | R$ 5,628,450 | R$ 5,029,327 | R$ 5,658,529 | R$ 1.347 |
Number of Units
Distribution (R$/Unit)
TRADI NG, LIQU I DITY & YI ELDS

R$ 10.74 MM
Monthly Volume

R$ 86.00
Market Price

Daily Average
R$ 1.00
Distribution/Unit June 2026 distribution
R$ 512 k
R$ 96.53

NAV per Unit

Unitholders
14.88%
Annualized DY based on market price
34,890

0.89x P/VP

13.95%
12-Month DY based on market price
DISTRIBUTION HISTORY
ASSET MON ITORI NG
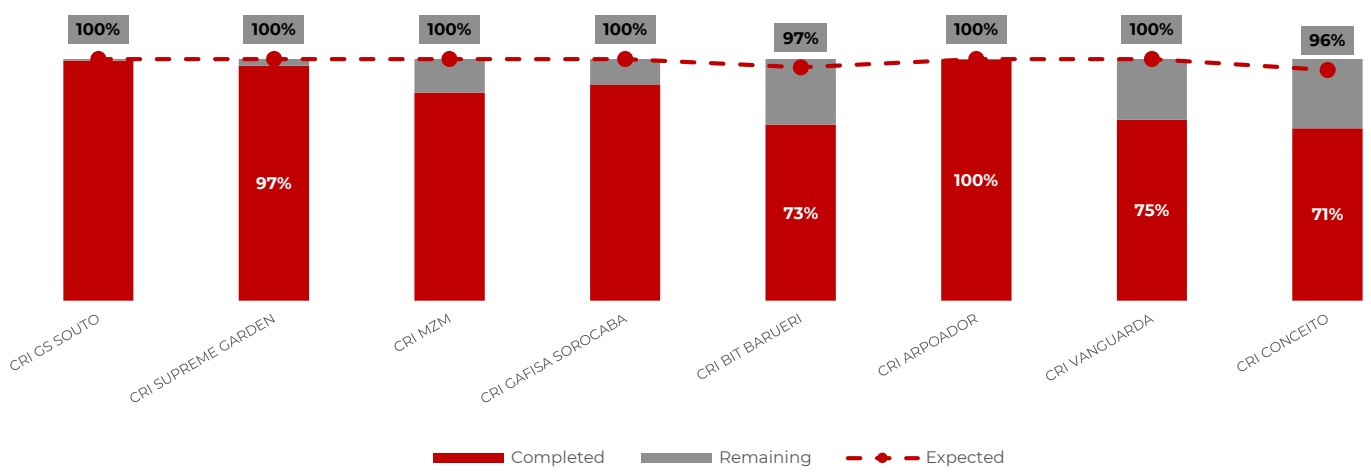
CONSTRUCTION PHYSICAL PROGRESS
RECEIVABLES PORTFOLIO DELINQUENCY
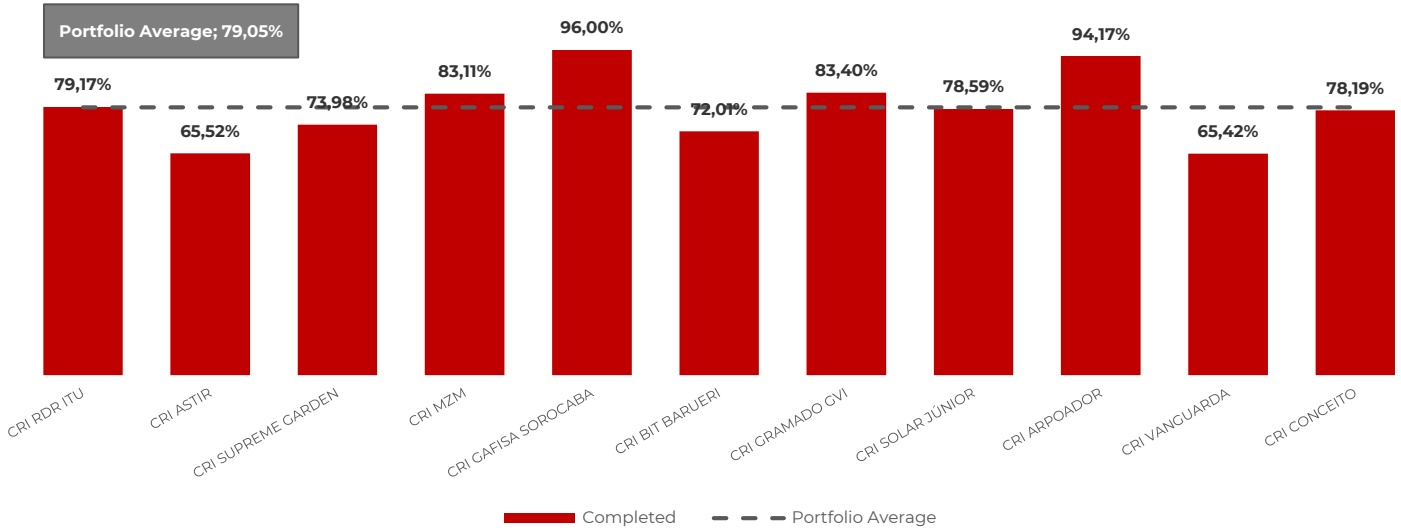
PORTFOLIO SALES LEVEL
ASSET MON ITORI NG
$$ \textsf { S U N O } \Big ( \textsf { A S S E T } \Big ) $$
PORTFOLIO AT PV & INVENTORY
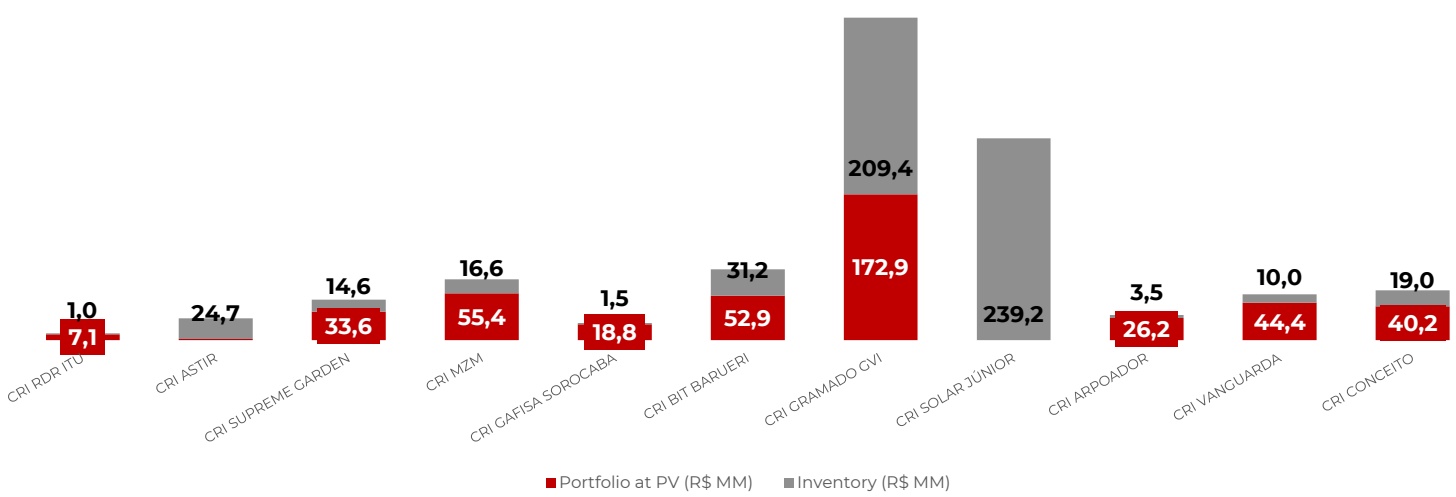
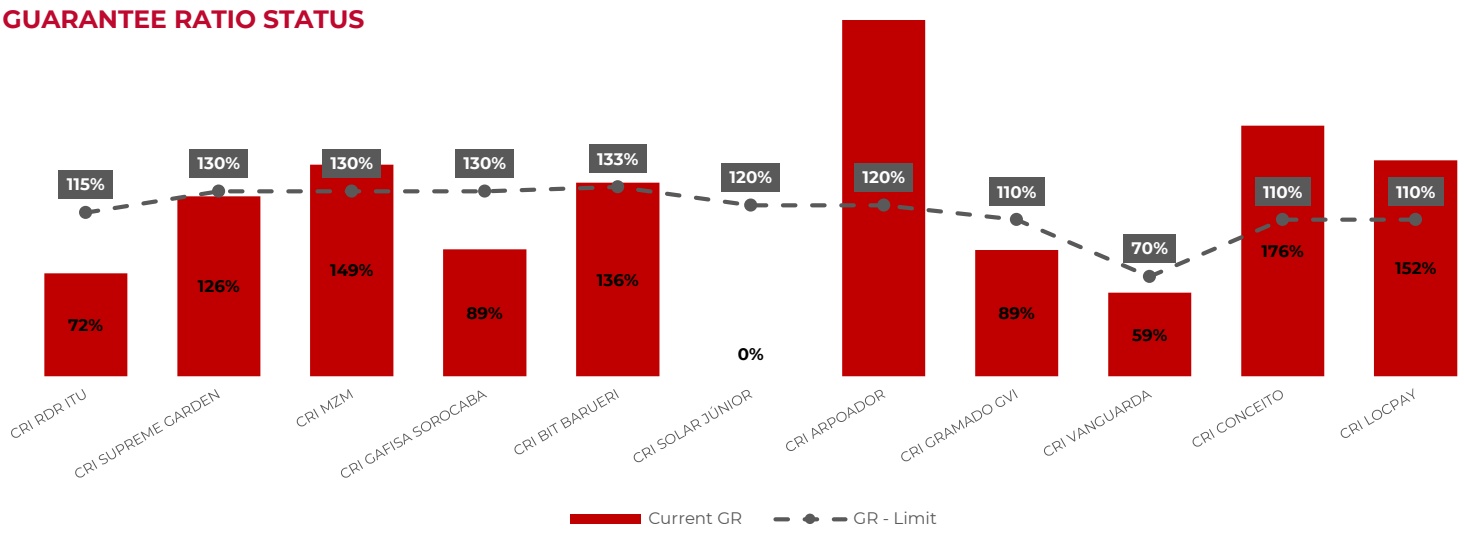
MAXIMUM RECEIVABLES PORTFOLIO CONCENTRATION
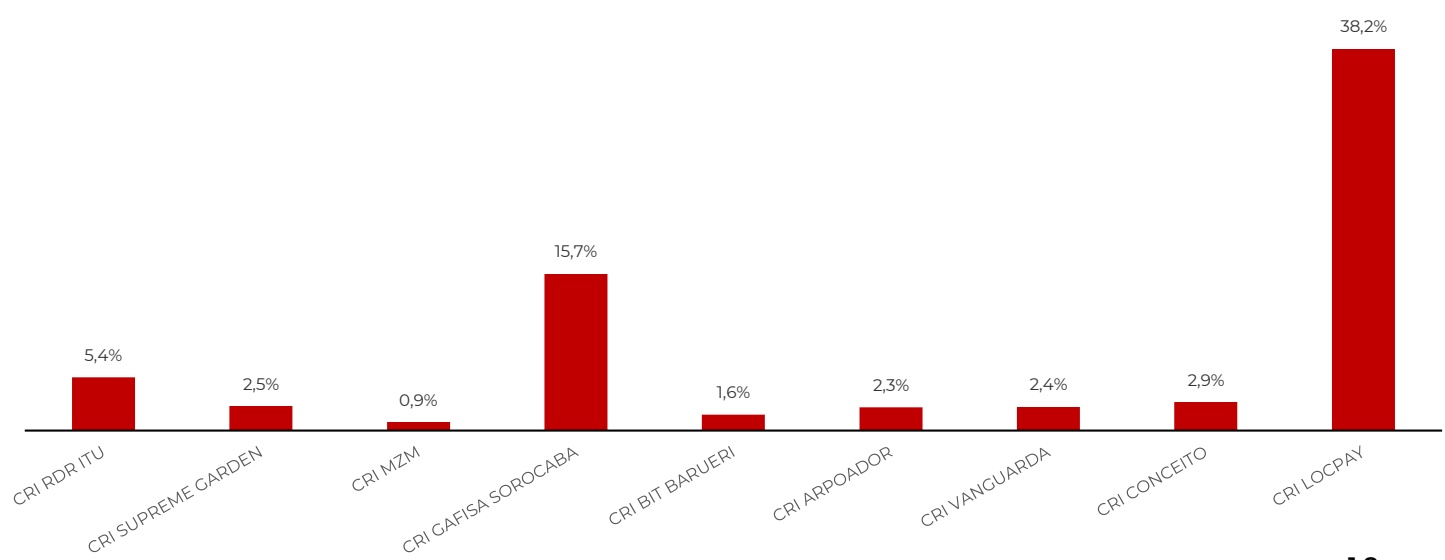
Detail of portfolio/repo positions (>0.5% of NAV)
| Debtor / Asset | State | Description | Collateral* | Maturity |
| Residential development in São Bernardo do Campo. Multiple series (I-V). IPCA + CRI MZM SP AF, CF & FR Jun/26 12.95%. Construction in final phase. | ||||
| CRI Supreme Garden | SC | Development in Itajaí. IPCA + 10.50%. Construction 93% complete, 74% sold. | AF, CF & FR | Jun/26 |
| CRI BIT SP Development in Barueri. CDI + 5.50%. Series I-IV. Construction 66%, sales 75%. AF, CF & FR Jul/26 | ||||
| CRI Gafisa Sorocaba | RJ | Gafisa WE development. CDI + 6.00%. Construction 87%, sales 92%. | AF, CF & FR | Sep/26 |
| CRI LATAM SP Aviation - Guarulhos maintenance center. IPCA + 5.73%. Atypical build-to-suit (BTS). AF & CF Aug/32 | ||||
| CRI GS Souto | MG | Energy - distributed-generation mini-hydro plants (CGHs). IPCA + 11.00%. Payoff expected. | AF & CF | Apr/26 |
| CRI MRV I Var. MRV corporate. IPCA + 6.50%. Backed by debentures. Clean Feb/29 | ||||
| CRI RDR Itu | SP | Development in Itu. IPCA + 12.00%. Construction 100%. In recovery. | AF | Matured |
| CRI OPY Health MG Healthcare - ONM Health (Opy). IPCA + 10.50%. Hospital PPPs. AF & CF Aug/31 | ||||
| CRI Itabira | MG | Energy - Itabira solar plant (UFV). IPCA + 11.00%. Operational. | AF & CF | Dec/38 |
| CRI Ceratti Magna SP Logistics warehouse in Vinhedo. IPCA + 8.50%. Magna and Ceratti leases. AF, CF & FR May/27 | ||||
| CRI AXS III | Var. | Energy - AXS EnergyTech. IPCA + 11.00%. Series III. | AF & FR | Jul/30 |
| CRI MRV II Var. MRV corporate. IPCA + 6.50%. 2nd series, debentures. Clean Feb/29 | ||||
| CRI Comporte | SP | Corporate - São Paulo city transport. CDI + 3.50% | AF & FR | Sep/30 |
| CRI Copagril PR Corporate - Agribusiness cooperative. IPCA + 6.50% AF & FR Jun/31 | ||||
| CRI Pesa/AIZ | PR | Corporate - Heavy machinery. IPCA + 5.5% and 7.0%. In recovery. | AF, CF & FR | Dec/37 |
| CRI Conceito | MA | Granular - Development in São José do Ribamar/MA. CDI + 6.50%. | AF, CF & FR | Oct/29 |
| CRI GF6 | MA | Granular - Land-subdivision portfolio in Imperatriz/MA. IPCA + 15.00%. | AF, CF & FR | Aug/33 |
| CRI Mahalo | ES | Granular - Development in Vila Velha/ES. CDI + 6.00%. | AF, CF & FR | May/30 |
| CRI Oliveira | SP | Corporate backed by a development in Sorocaba/SP. IPCA + 12.68%. | AF, CF & FR | May/30 |
| CRI Wimo IV | Var. | Granular - Senior home equity. IPCA + 8.00%. | AF, CF & FR | Jan/37 |
| CRI LocPay | Var. | Senior granular - Rental assignment. Fixed at 23.87% p.a. | CF & FR | Jul/31 |
| CRI Mitre 2025 | SP | Corporate - Mid-to-high-end developer in São Paulo/SP. | Clean | Dec/29 |
| CRI Esatas | SP | Contractual - Campinas/SP airport lease receivables. IGP-M + 8.0%. | AF, CF & FR | Apr/36 |
| CRI Rede Duque | SP | Corporate - BR fuel-station receivables in SP. IPCA + 8.20%. | AF, CF & FR | Sep/33 |
| CRI Arpoador | ES | Granular - Development in Vila Velha/ES. CDI + 6.00%. | AF, CF & FR | Jan/28 |
| CRI Vanguarda | PI | Granular - Development in Teresina/PI. INCC + 11%. In recovery. | AF, CF & FR | Matured |
| Real Estate Fund | ||||
| TGAR11 - TG Auro hybrid FII. Annualized DY 14.38%. - - | ||||
| SNME11 | - | Hybrid FII managed by Suno Asset. Annualized DY 14.14%. | - | - |
| INOI | - | Logistics-warehouse FII in Paraná, managed by Inter Asset. | Subord. | - |
| VRTM11 | - | Multi-strategy FII managed by Fator. | - | - |
| RECD11 | - | Receivables FII managed by Real Estate Capital. | - | - |
| Idees Pompéia | SP | FII for a real-estate development in São Paulo/SP | - | - |
AGTs OF TH E MONTH
| Asset | Date | Agenda | Resolution |
| (i) Not to declare early maturity arising from the failure to fund the payment of Remuneratory Interest in February and April 2026, which caused the Liquidity Reserve to fall out of compliance in May 2026. An additional 60-day period was granted to bring this reserve back into compliance. (ii) Not to declare early maturity for the late submission (made on March 26, 2026) of the Use-of-Proceeds Report for the period ended January 2026. (iii) Not to declare early maturity due to the failure to submit the trial balance for the quarter ended In favor of all. March 2026, granting an additional 90 days for its submission. CRI BIT June 3, 2026 Measures aimed at supporting (iv) To engage the law firm Negrão Ferrari Advogados to act as Legal Advisor for the issuance's legal construction progress and protecting counsel, with costs paid by the Segregated Estate. investors in the project's final phase. (v) To present the financial statements of the Segregated Estate and the respective audit reports for the fiscal years ended March 2023, 2024 and 2025. (vi) To authorize the Issuer to partially transfer funds from the Liquidity Reserve to the Construction Reserve after the 4th CRI Series is paid in, provided a minimum balance of R$ 1,000,000.00 is kept in the Liquidity Reserve until the occupancy permit ("Habite-se") is issued. | |||
| CRI Gafisa | June 3, 2026 | (i) Not to declare early maturity of the Commercial Notes and the CRIs due to the non-payment of the installment (PMT) for May 2026, in the amount of R$ 3,203,001.89. (ii) To add the unpaid May 2026 PMT to the CRIs' outstanding balance, using the value on the default date and waiving penalties, interest or late charges. (iii) To change the payment frequency of the Remuneration and Amortization from monthly to a single (bullet) payment on the Maturity Date, to be paid after the occupancy permit ("Habite-se") is issued. | In favor of all Renegotiation of the payment schedule in the final construction phase. |
| CRI LocPay | June 3, 2026 | (i) To authorize the issuance of 2 new series (3rd Series comprising Senior CRIs of up to R$ 12,000,000.00; and 4th Series comprising Junior CRIs of up to R$ 3,000,000.00), totaling up to R$ 15,000,000.00. Both will keep the 23.87% p.a. remuneration and the same backing in lease-based CCIs (real-estate credit notes) as the current series. (ii) To amend the Securitization Agreement (applicable to all series) to: a) Extend the CRIs' maturity from July 31, 2028 to July 31, 2031. b) Adjust the Payment Waterfall, extending the deadline to acquire new Real-Estate Credits to August 1, 2030. c) Modify the Eligibility Criteria and Excluded Risks (e.g., reduce the minimum term to 1 month, extend the maximum term to 24 months, adjust concentration limits, require a minimum Serasa score of 400, and require lease collateral on at least 90% of the portfolio). d) Remove the "KYP Compliance" requirement from the real-estate agencies' Document File. e) Add an obligation for LocPay to repurchase defaulted credits if the delinquency rate exceeds the Subordination Ratio. f) Establish that the Senior CRIs will be paid in tranches of up to R$ 1,500,000.00. (iii) To authorize LocPay to issue new lease-based CCIs to back the New Series. (iv) To authorize the engagement of the service providers required for the new issuance, borne by the Segregated Estate or by the Debtor. (v/vi) To authorize the signing of amendments to the Transaction Documents and the taking of all actions necessary to implement these matters. | In favor of all. Increase the CRI's size and term and renegotiate the portfolio's eligibility criteria. |
SNAG11
SNFZ11
SNCIM1

SNEL11
SNID11
SNME11


SUNO PREV
SNFF11
FIC FIA
LEARN MORE


IG SUNO ASSET

YT SUNO ASSET
SNCI11 - SUNO ASSET WEBSITE
SUNO GLOBAL EQUITIES

What is SNCI11?
A real-estate credit fund (FII) by Suno Asset that invests in real-estate receivables (CRIs), focusing on development, land subdivision, home equity and energy, seeking return and diversification.
Moderate (middle-risk), with 36 diversified CRIs, a weighted rating of A3, an average LTV of 69.60%, and active management with continuous monitoring of the credits and collateral.
To generate predictable, low-volatility monthly income, with diversified investments in CRIs — residential development, land subdivisions, energy and corporate credit.
Are distributions taxed?
Where can I find official reports and information?
What is the fund's objective?
What is the risk profile?
For individual investors, distributed income is exempt from income tax under Brazilian FII legislation (Law 8,668/93).
On the Suno Asset website → suno.com.br/asset/fundos/snci11
Where does the fund invest?
Mainly in CRIs (≈60% IPCA, ≈20% CDI), FIIs (≈11%), repos and cash, diversifying across development, energy and healthcare.
Are the units liquid?
Yes. Traded on the B3 exchange (SNCI11), with average volume of R$ 0.51 MM/day and more than 34.9 thousand unitholders.
How does the distribution work?
Monthly payments. In Jun/26: R$ 1.00/unit, annualized DY of 13.95%. Guidance: R$ 1.00 to R$ 1.10 in 1Q26.
What does P/VP mean?
Market price / net asset value. SNCI11 trades at 0.89x, a ~11% discount to NAV.
How are the assets managed?
Active origination in the real-estate market, rigorous credit analysis and continuous monitoring of the collateral and construction works.
GLOSSARY OF KEY
TERMS
This English report keeps standard Brazilian market acronyms. Key terms are explained below.
FII: Fundo de Investimento Imobiliário – Brazilian listed real-estate investment fund; income distributed to individuals is generally income-tax exempt.
CRI: Certificado de Recebíveis Imobiliários – real-estate receivable certificate; a securitized fixed-income instrument backed by property-related credits.
CCI: Cédula de Crédito Imobiliário – real-estate credit note evidencing a property credit (e.g., lease or mortgage receivables).
Securitization company (securitizadora): the issuer that securitizes credits into CRIs and manages each deal's Segregated Estate.
Segregated Estate (patrimônio separado): the ring-fenced pool of assets and obligations of a given CRI series, insulated from the issuer's other deals.
IPCA: Brazil's official consumer-price inflation index.
IGP-M: a Brazilian general price index (inflation), widely used in rents and contracts.
INCC: Brazil's national construction-cost index.
CDI: interbank deposit rate; the main Brazilian floating-rate benchmark (tracks the Selic).
Selic: the Central Bank of Brazil's policy interest rate.
COPOM: the Central Bank's Monetary Policy Committee, which sets the Selic.
B3: the Brazilian stock exchange (São Paulo).
IFIX: the benchmark index for Brazilian listed real-estate funds.
DY (dividend yield): distributions over the trailing 12 months (or annualized) divided by the unit price.
P/VP: price-to-NAV: market price of the unit divided by its net asset value (NAV) per unit.
PL / NAV: net assets (patrimônio líquido) – the fund's net asset value; "% of NAV" and "% of PL" are used interchangeably.
LTV: loan-to-value: outstanding credit divided by the appraised value of the collateral.
AGT: Assembleia Geral de Titulares – general meeting of CRI holders, where deal resolutions are voted.
Guarantee Ratio (GR / Razão de Garantia): collateral (receivables plus inventory) over the outstanding balance of a CRI.
Fiduciary lien (alienação fiduciária): security interest transferring title of the property to the creditor until the debt is paid.
Fiduciary assignment (cessão fiduciária): assignment of receivables or rights as collateral to the creditor.
Occupancy permit (“Habite-se”): municipal certificate that a building is complete and fit for occupancy.
Development (incorporação): real-estate development: the legal and commercial structuring and construction of a project for sale.
Repo (operação compromissada): repurchase agreement; a short-term secured funding or lending transaction.
“Minha Casa, Minha Vida” (MCMV): Brazil's federal affordable-housing program.
CEF (Caixa Econômica Federal): the state-owned savings bank and a major mortgage lender.
GERIC: Caixa's engineering approval unit for financing residential developments.
FGC: Fundo Garantidor de Créditos – Brazil's credit guarantee fund (it does NOT guarantee investment funds).
Dation in payment (dação em pagamento): settlement of a debt by transferring assets (e.g., units) to the creditor.
Middle-risk: a moderate risk/return credit profile, between conservative and high-yield.
FITs (frações ideais de terreno): ideal (undivided) fractions of land, used in development financing.
Fractional (multipropriedade): shared/fractional ownership of a property (timeshare-style).
NOTICES AN D DISCLAI M ERS
This document is a free English translation of the management report (Relatório Gerencial) of Suno Recebíveis Imobiliários Fundo de Investimento Imobiliário (SNCI11), prepared solely for the convenience of readers who do not read Portuguese. The Portuguese version is the sole official version, is the one filed with the Brazilian Securities and Exchange Commission (Comissão de Valores Mobiliários – CVM) and disclosed under applicable Brazilian regulation and ANBIMA self-regulation, and prevails over this translation in the event of any divergence, omission or doubt as to interpretation. It does not replace or amend the Portuguese version, the Fund’s bylaws (regulamento) or any other document of the Fund.
All figures refer to the same reference date as the Portuguese version and are stated in Brazilian reais (R$), the Fund’s functional currency, in which its assets, liabilities and results are recorded and reported to CVM and ANBIMA. Suno Asset assumes no obligation to update this translation.
This document is informational only and does not constitute an offer, solicitation, advertisement or recommendation to buy, sell or subscribe for any security, nor legal, tax or investment advice. SNCI11 is a Brazilian real estate investment fund (Fundo de Investimento Imobiliário – FII), regulated and supervised by CVM, registered for public distribution and admitted to trading exclusively in Brazil, on B3 S.A. – Brasil, Bolsa, Balcão. It is not registered for offer or distribution in any other jurisdiction.
This document is not directed at any person in any jurisdiction where its distribution or use would be contrary to applicable law or would require any registration or authorisation not already obtained. Readers access it on their own initiative and are responsible for observing the rules applicable in their own jurisdiction, including tax and exchange control rules.
Estimates, projections and distribution guidance herein reflect the current judgement of Suno Asset as at the date of disclosure and are subject to change without notice. They are not free from error, offer no assurance that the scenarios described will occur, and do not constitute a promise or guarantee of return, of any future distribution or of capital preservation.
Investment funds are not guaranteed by the fund’s administrator, by the portfolio manager, by any insurance mechanism or by the Brazilian credit guarantee fund (Fundo Garantidor de Créditos in Portuguese, or “FGC”). Past performance is not a guarantee of future results. Investors are advised to carefully read the Fund’s prospectus and bylaws (regulamento) before investing. Investors must be prepared to accept the risks inherent to the various markets in which investment funds operate and, consequently, possible fluctuations in the invested capital. The Administrator is not liable for any errors or omissions in this material, nor for the use of the information contained herein. In addition, the Administrator is not liable for investors’ decisions regarding the matters addressed in this material, nor for the acts or facts of professionals and specialists consulted by the investor.
This material does not relate to the specific investment objectives, financial situation or particular needs of any specific recipient and should not be relied upon as the sole source of information in the investor’s decision-making process. Before deciding, the investor should carry out — preferably with the assistance of a duly qualified professional — a careful assessment of the product and its respective risks against his or her personal objectives and risk tolerance (suitability). The Portuguese version of this report and the Fund’s other official documents are available at https://www.suno.com.br/asset/fundos/snci11.